






Breakout DAX 15Min
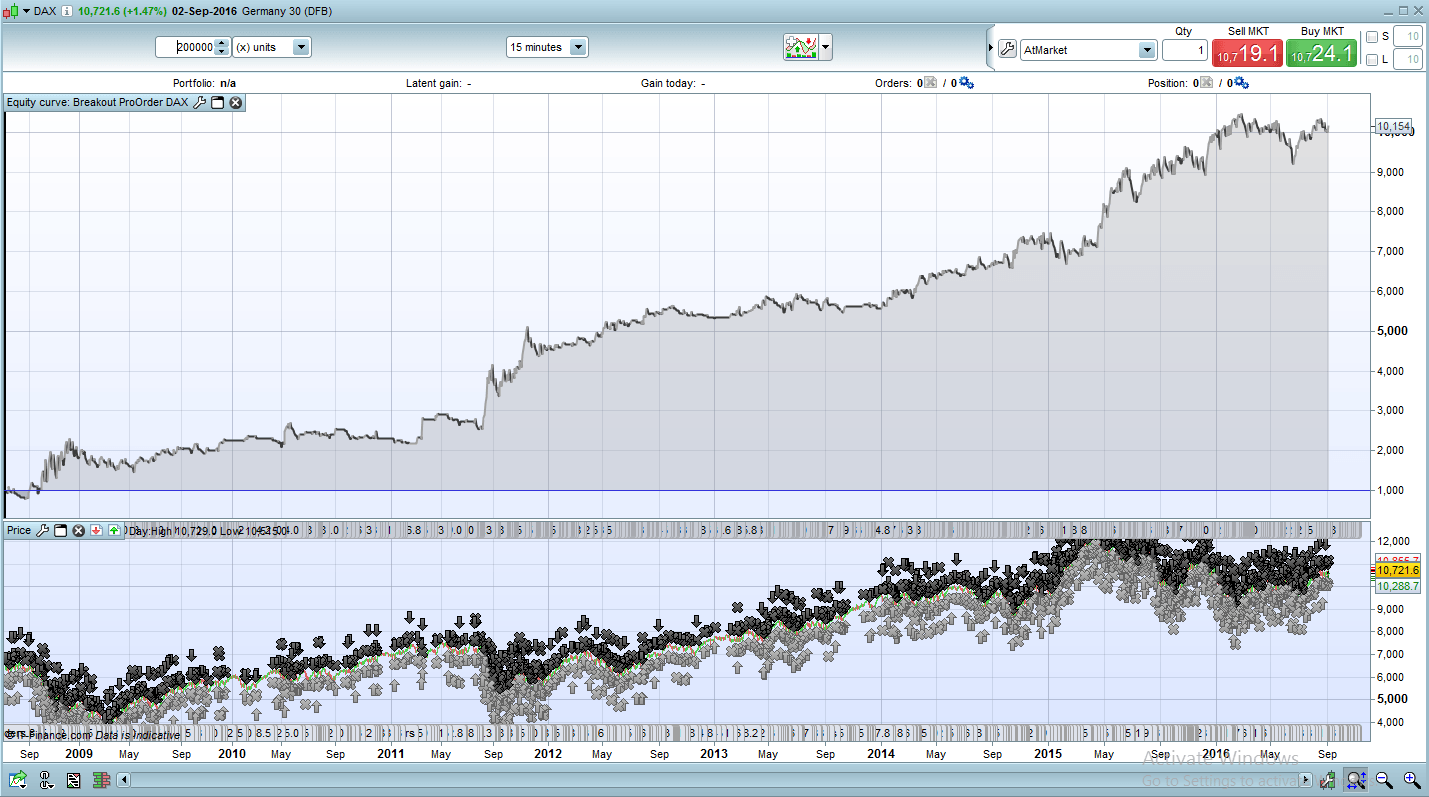
Firstly, a big thank you to Nicolas for this great site and for originally introducing us to the CAC Breakout using the same code here.
I set about testing this strategy on other markets due to the fact you can backtest 8 years of data with 200,000 units on the 15Min time-frame. The other massive plus is no fake profits and only 26, 0 bars in 1500 trades! 🙂
In this version I am using a fixed position size but you can activate the re-invest system if you are happy with that. It makes for an interesting ride!
I stuck to the rules of not over optimising/curve fitting by using an IN/OUT sample as documented here. This ran from July 2008 – Jan 2014.
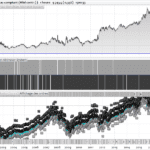
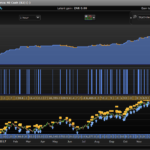
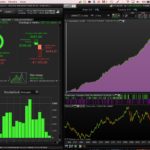
The results above are £1 Per Point, £1000 Start and 1.5 Spread.
I am live trading this with real money with minimum stakes to test. IG have now reduced the PPP from £2 to £1 just recently. This is very handy for forward live testing.
All times in the code are UK so please adjust to your timezone.
I have some more of these ported to other markets but need to spend a little more time getting them right before posting in the library. Expect them soon.
I have not had enough time to test different time frames. Maybe I will try that next if time allows.
Good luck and enjoy your weekend.
//-------------------------------------------------------------------------
// Main code : Breakout ProOrder EN DAX
//-------------------------------------------------------------------------
// We do not store data until the system starts.
// If it is the first day that the system is launched and if it is afternoon,
// it will wait until the next day for defining sell and buy orders.

//All times are UK Time Zone

DEFPARAM PreLoadBars = 0

// Position is closed at 20h00 PM
DEFPARAM FlatAfter = 200000

// No new position will be initiated after the 16:00PM candlestick. Any existing orders cancelled at 16:30pm
LimitHour = 161500

// Market scan begin with the 15 minute candlestick that closed at 8:30AM
StartHour = 081500

// The 24th-31st days of December will not be traded because the market closes early.
IF (Month = 5 AND Day = 1) OR (Month = 12 AND (Day = 24 OR Day = 25 OR Day = 26 OR Day = 30 OR Day = 31)) THEN
TradingDay = 0
ELSE
TradingDay = 1
ENDIF

// Variables that would be adapted to your preferences
if time = 074500 then
//PositionSize = max(1,1+ROUND((strategyprofit-1000)/1000)) //gain re-invest trade volume
PositionSize = 1 //constant trade volume over the time
endif
MaxAmplitude = 170
MinAmplitude = 22
OrderDistance = 9
PourcentageMin = 19

// Variable initilization once at system start
ONCE StartTradingDay = -1

// Variables that can change in intraday are initiliazed
// at first bar on each new day
IF (Time <= StartHour AND StartTradingDay <> 0) OR IntradayBarIndex = 0 THEN
BuyTreshold = 0
SellTreshold = 0
BuyPosition = 0
SellPosition = 0
StartTradingDay = 0
ELSIF Time >= StartHour AND StartTradingDay = 0 AND TradingDay = 1 THEN

// We store the first trading day bar index
DayStartIndex = IntradayBarIndex
StartTradingDay = 1
ELSIF StartTradingDay = 1 AND Time <= LimitHour THEN

// For each trading day, we define each 15 minutes
// the higher and lower price value of the instrument since StartHour
// until the buy and sell tresholds are not defined
IF BuyTreshold = 0 OR SellTreshold = 0 THEN
HighLevel = Highest[IntradayBarIndex - DayStartIndex + 1](High)
LowLevel = Lowest [IntradayBarIndex - DayStartIndex + 1](Low)

// Spread calculation between the higher and the
// lower value of the instrument since StartHour
DaySpread = HighLevel - LowLevel

// Minimal spread calculation allowed to consider a significant price breakout
// of the higher and lower value
MinSpread = DaySpread * PourcentageMin / 100

// Buy and sell tresholds for the actual if conditions are met
IF DaySpread <= MaxAmplitude THEN
IF SellTreshold = 0 AND (Close - LowLevel) >= MinSpread THEN
SellTreshold = LowLevel + OrderDistance
ENDIF
IF BuyTreshold = 0 AND (HighLevel - Close) >= MinSpread THEN
BuyTreshold = HighLevel - OrderDistance
ENDIF
ENDIF
ENDIF

// Creation of the buy and sell orders for the day
// if the conditions are met
IF SellTreshold > 0 AND BuyTreshold > 0 AND (BuyTreshold - SellTreshold) >= MinAmplitude THEN
IF BuyPosition = 0 THEN
IF LongOnMarket THEN
BuyPosition = 1
ELSE
BUY PositionSize CONTRACT AT BuyTreshold STOP
ENDIF
ENDIF
IF SellPosition = 0 THEN
IF ShortOnMarket THEN
SellPosition = 1
ELSE
SELLSHORT PositionSize CONTRACT AT SellTreshold STOP
ENDIF
ENDIF
ENDIF
ENDIF

// Conditions definitions to exit market when a buy or sell order is already launched
IF LongOnMarket AND ((Time <= LimitHour AND SellPosition = 1) OR Time > LimitHour) THEN
SELL AT SellTreshold STOP
ELSIF ShortOnMarket AND ((Time <= LimitHour AND BuyPosition = 1) OR Time > LimitHour) THEN
EXITSHORT AT BuyTreshold STOP
ENDIF

// Maximal risk definition of loss per position
// in case of bad evolution of the instrument price
SET STOP PLOSS MaxAmplitude
//SET TARGET PPROFIT 190
Comments
You must be logged in to post a comment.

I tried this one out recently, and wasn't profitable for me.


Hi ... Thanks a lot for sharing this strategy. I have backtested this and works fine on DAX. Only concern is bigger position size. It does not seem to behave well if I have a position size of 10 (for e.g.) Can you suggest if this strategy is supposed to work only with small position sizes ?

Hi, I am going to use this system tomorrow with £1 trades. I'll post my results. Do you have a direct email by any chance?
Ollie

Love the comments preceding each line / block of code ... so useful for the likes of me who find it difficult (near impossible often) to interpet complex code written by others.
I know full explanatory comments are more time consuming, so a big thank you from me goes to Cosmic, good work!
GraHal


Yes, not great lately. I stopped this live at the end of last year. Will wait to see when the right time is to put it back on. Just shows you that even following all the rules to avoid curve fitting etc, algo's can still bite you!