






Code "Mark Larsen - Bollinger Strategy"
Hello Guys,
In 2013, I did see a strategy of Mark Larsen on Youtube. I was very happy to see this video, and decided to use this strategy with real money.
Guess what ?
I did loose much !
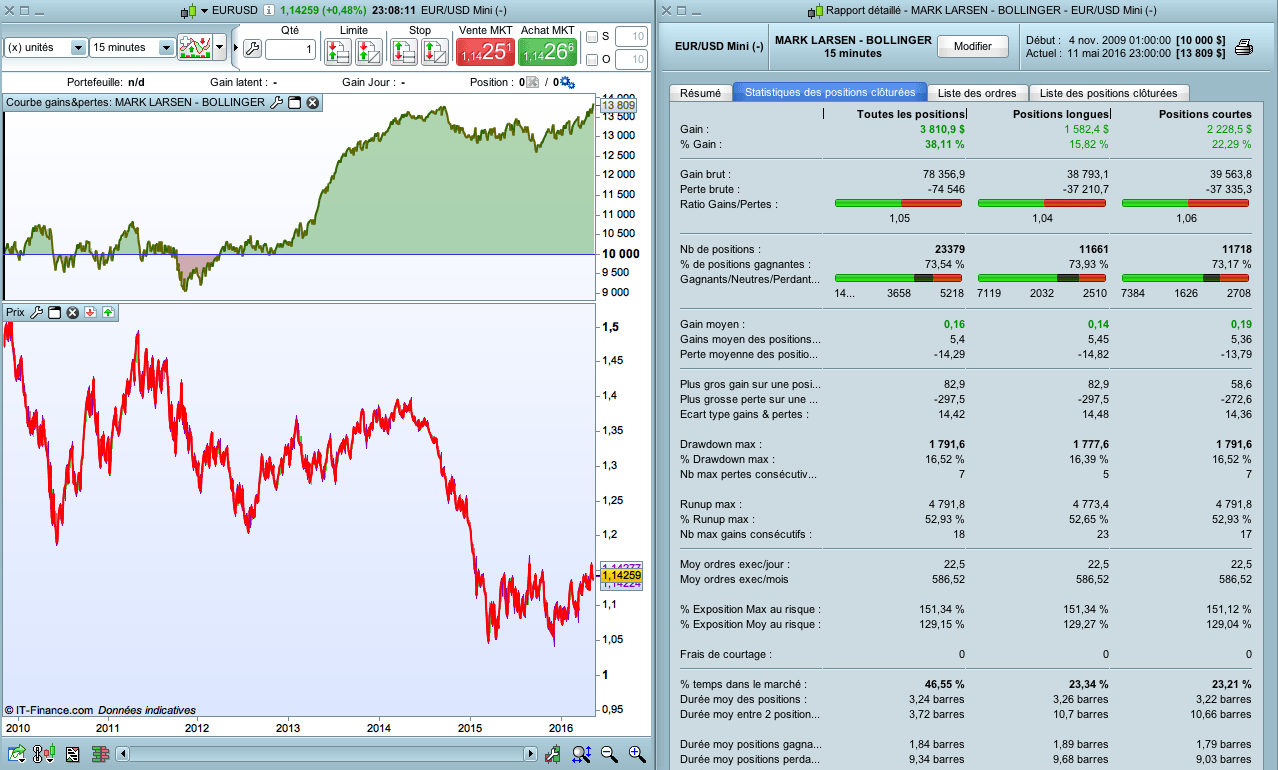
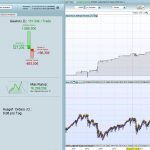
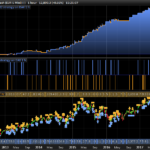
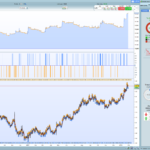
Now I can backtest it. The result isn’t so sexy (EUR/USD, timeframe M15).
Maybe I did wrong with some entry rules ?
Here is the code :
DEFPARAM CumulateOrders = False

n = 1

BollUP = BollingerUp[10](close)
BollDown = BollingerDown[10](close)

// ACHAT
ca = close > BollDown and low < BollDown
IF ca THEN
Buy n shares at market
ENDIF


// VENTE
cv = close < BollUp and high > BollUp
IF cv THEN
Sellshort n shares at market
ENDIF


// SORTIE
Sell at Average[14](close) limit
Exitshort at Average[14](close)limit
Comments
You must be logged in to post a comment.

At least there should be some moving average that has also reverted into the opposite direction, before a position is opened. Otherwise a cumulation of wrong positions will be opened, when the market goes strongly into one direction and never reverts back on the short-term scale.

Cette stratégie est quasi similaire de celle publiée sous le titre "nice price strategy". Sauf que l'auteur de mémoire avait ajouté un indicateur (DI+ et DI-). Pour ma part, je l'ai un peu retouché en utilisant les bandes de Kellner et le STO mais bon il faut rester vigilant. Bonne soirée.
It's a classical mean reverting strategy used by many people with many variants. It makes sense in ranging market, when price has derivated from 2 standard deviation from its mean, it would come back to it. While market is trending, you loose because this strategy is contrarian.
I have recently reverse engineered an averaging down strategy that were popular at mql5 with the same kind of entries, the guy re-entered each time close were within the bollinger bands with a step from the average price of the basket, then close the whole orders on the opposite bands. While it were making huge profit if opposite band was above the average price, it could also be dangerous to accumulate orders in a long run.
My thought is that there are a lot to explore in mean reversion theory but the loss must be cut quickly as the 'mean revert signal' given at last bar is already false on the next one, because average of price has already changed since that information..
Thanks for contribution.
This works excellent on range bound I tried , give 90% win rates on dax , 3 min chart. can some one try to throw some light on this to avoid a sell or buy or when big trend started . in other word we need to one or more condition to not place order when range is broken big trend started