






Cumulative RSI 2 periods strategy
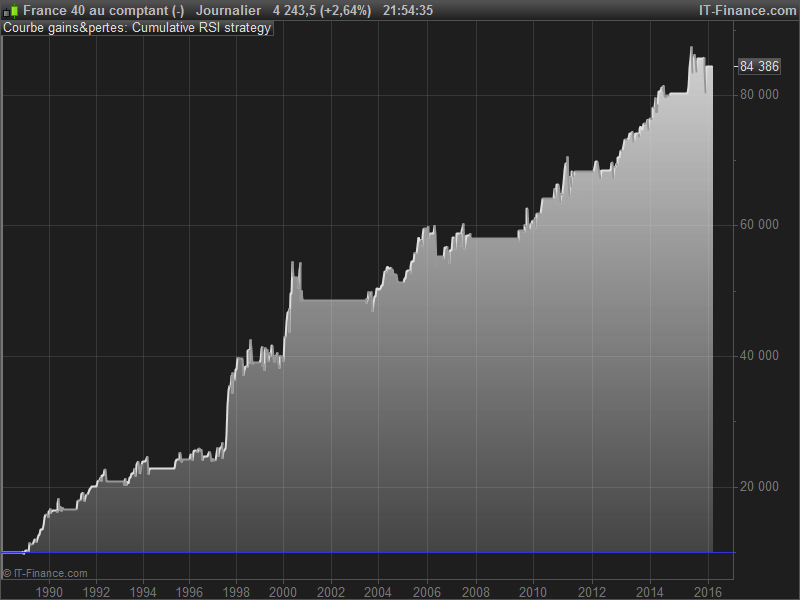
Long only strategy that performs extremely well on any world indices and beyond on a daily timeframe. I will certainly do much exploration of this very short term mean reversion strategy, as it seems very powerful without doing any change on triggers.
The main trigger is based of a “cumulated RSI” over the 2 recent periods while trade are launch only if the price Close is above a 200 period moving average.
When the cumulated RSI enter in oversold territory, we expect the price to return to its mean, on the bullish trend. We exit the market when the CRSI gain overbought area above the 65 level.
As for my current test : (with exactly the same code on CFDs)
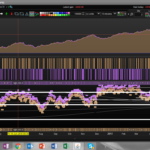
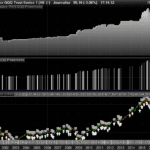
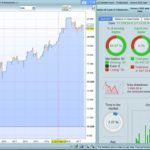
CAC40 : (featuring picture) : 10€ /contracts, 1 contract per trade since 1988 = +370% / % Drawdown max = 12.7%
IBEX35 : 2€ / contract, 1 contract per trade since 1994 = +134.33% / % Drawdown max = 25.6%
SP500 : 1€ / contract, 10 contract per trade since 1984 = +95.33% / % Drawdown max = 8.08%
//indicator
Period = 2
CUMRSI = SUMMATION[Period](RSI[Period](close))
AVG = average[200](close)

//initial lot
initLOT = 10

IF NOT LongOnMarket AND Close>AVG AND CUMRSI<35 THEN
  BUY initLOT CONTRACTS AT MARKET
ENDIF

If LongOnMarket AND CUMRSI>65 THEN
  SELL AT MARKET
ENDIF
Comments
You must be logged in to post a comment.

Aucune immobilisation du capital. Quel est le drawdown du buy & hold ? Je ne l'ai pas calculé moi même, mais cela a dut être difficile en 2008 et 2012 ? Après coup, lorsque l'on a toutes les informations à disposition, certaines stratégies auraient été meilleures que d'autres. Il est vrai que l'on a coutume de comparer les stratégies d'interventions automatique avec le buy&hold sur les indices et les actions, malgré cela, une stratégie qui fait 370% à elle seule et qui peut être incorporé à un portefeuille plus vaste de stratégies automatiques est valable selon moi.
Cette stratégie de mean reversion est tellement simple, qu'il aurait été dommage de ne pas la proposer à tous :)


Very nice and logical strategy...
Could be used for example to take orders on the french "PEA" (Plan d'Epargne Actions).
"RSI 14" is still alive !
Best regards ;)

A lot of quantitative traders believe that the RSI default '14' periods is dead, although for what it were developed to : spot the overbought and oversold areas of the price development over time. It does not mean that the RSI formula is mean-less, but not still effective with its default value for whom it were set, back in 1978 by M.Wilder! The cumulative RSI is nothing more than another indicator, it borrows the formula from RSI, cumulate 2 periods and that's all. Why 2 periods for this one? because price behaviour, return to the mean fastly, no more no less. Automatic trading and quant strategy development are a vast playground, go on, play with period, create another indicator from this one or a fresh new one, if it works you were right, if not you still have an entire life to learn maths :)

Very interesting strategy and easy one! Have you tested it in any other markets than your examples??
Not yet. A nice thing to do would be to implement another strategy into this one when price go bearish and dive under the MA200. Of course, it works well because of the mean reverting thing over a nice bullish movement, but adding other strategy over this one would be great, diversification is the key. As i said in this post, i need to work further on it, you are right, it is very interesting!
Hello, Is there a ProRealCode indicator behind this strategy?