






DAX Trend following - 2-hours timeframe
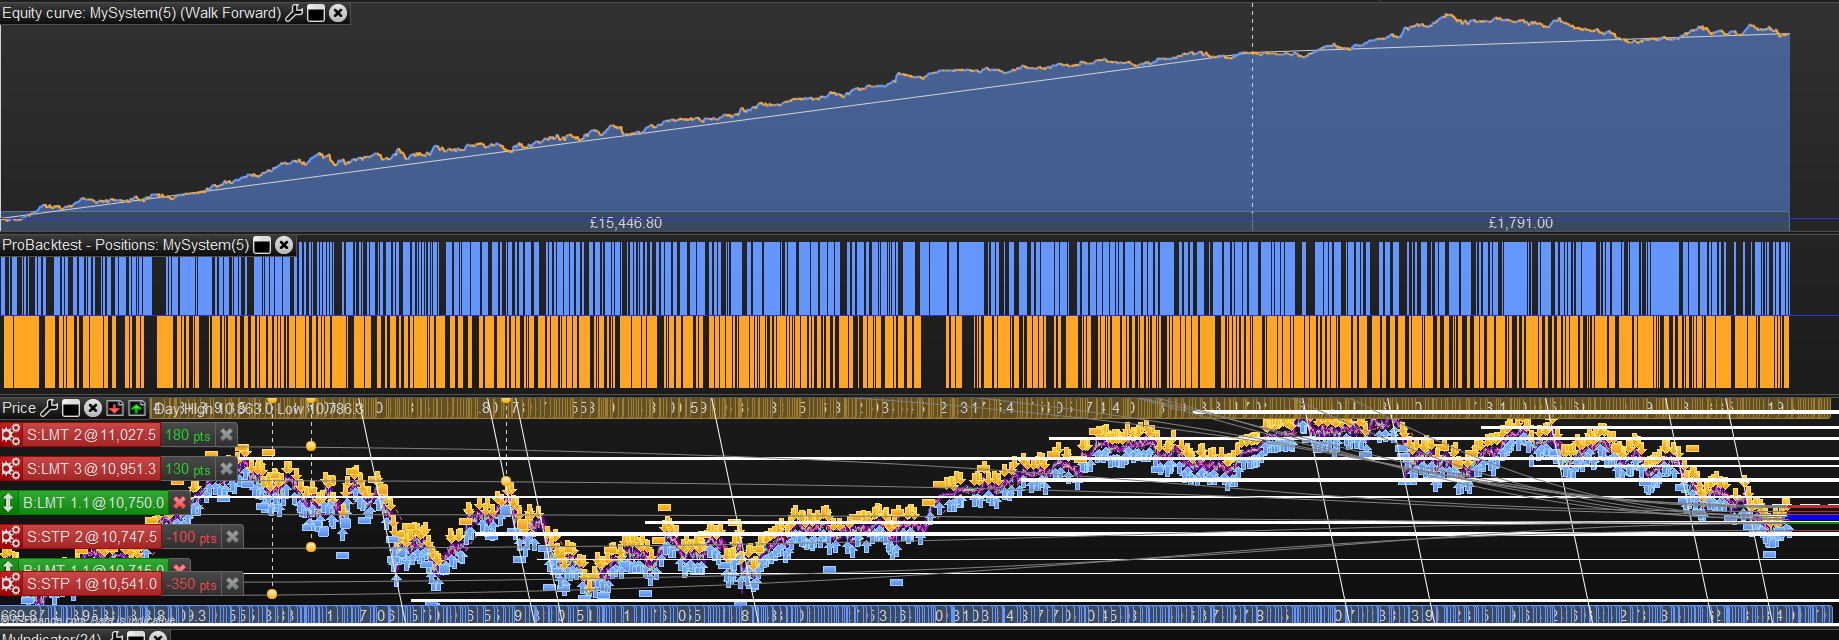
This DAX automatic trading strategy on the 2-hours timeframe, use a basic cycle oscillator to test “overbought” and “oversold” areas to open new orders.
All orders have stoploss and takeprofit.
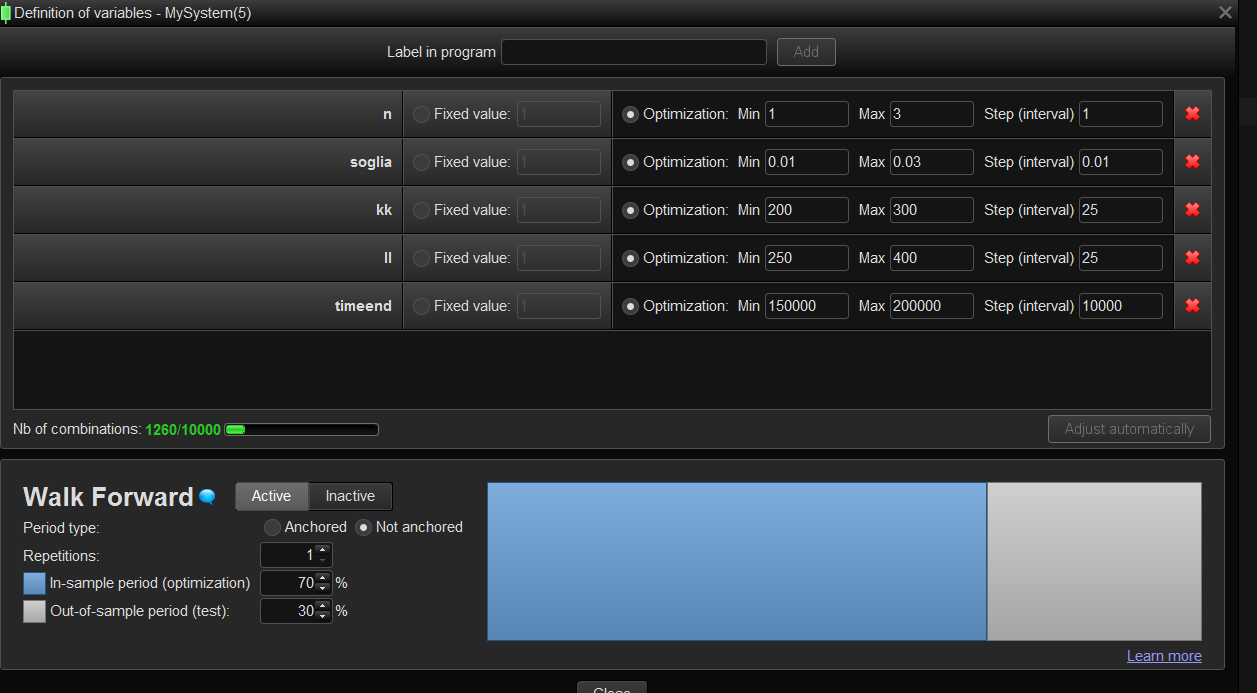
Results attached are from walk forward analysis with 1 OOS period proving robustness of the optimized variables. Variables to be optimized are also described in one of the attached picture.
Discussions about the strategy are running here: Dax Trrend Following, h2 time zone:uk
defparam cumulateorders = false
n=2
soglia = 0.02
timestart = 90000
timeend = 180000
profitti = 275
perdite = 350
timeok = time>=timestart and time<=timeend

c = (sin(atan((close-open[n])/open[n]*100/n)))
if c crosses over soglia and timeok  then
 buy 1 contract at market
endif

if c crosses under -soglia and timeok  then
 sellshort 1 contract at market
endif

set target pprofit profitti
set stop ploss perdite
Comments
You must be logged in to post a comment.
derschnee spiace a me che non riesci a replicarla. Prima di esprimere giudizi pensaci 2 volte.

Ciao Francesco, ho provato anch'io con fuso italiano cambiando i profitti e le perdite in punti ma il risultato non cambia. Ho aggiunto anche lo spread a 1 punto dato che mancava ma sono sempre in perdita sia che parto nel 2018 o 2017 fino ai giorni nostri. Grazie
ok, fammi sapere come ti viene, ciao
timestart = 90000 timeend = 180000 se lavorate con fuso italiano mettete timestart 100000 e timeend 190000 non dovrebbe cambiar el asostanza comunque,

You are most welcome!

c = (sin(atan((close-open[n])/open[n]*100/n))) this is the indicator. Itis a measure of the angle made by the price. I invented it, dont know if it is useful or not but I found that it worked well with the dax
ciao Francesco vorrei contattarti su facebook o in privato. Grazie