






Internal bar strength QQQ strategy
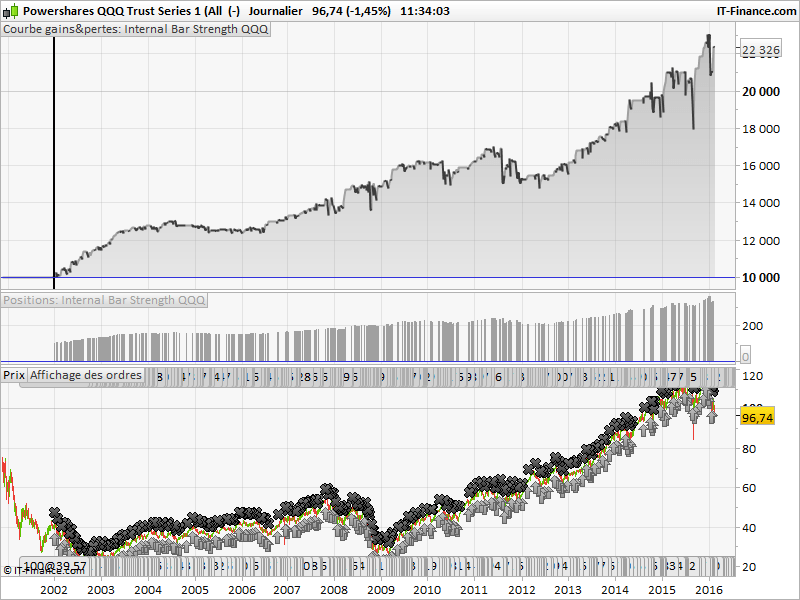
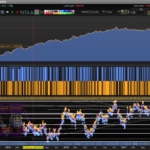
Here is a simple “long only” automated strategy built upon the mean reversion behaviour of the QQQ ETF. It uses the Internal Bar Strength indicator which represent the weight of the closing price related to the day’s range. It is a simple indicator that point the fact that deepest close would regain on the few next days. This indicator is the same as a stochastic oscillator with only 1 period = short term deviation from the price mean would expect that price will came back to it.
When the IBS (or stochastic oscillator) fall below the 10 level, buy at next open. Close the trade if a candle close above the previous day high.
I also add a dynamic lot calculation made upon the strategyprofit. You can change the value of the “initial lot” (100 shares at start) and the “step profit” which add more shares whenever the strategy gain a new stepprofit (50$ by default).
This strategy would be adapted to other indices, i will certainly go forward on it.
//indicator
STO =  (Close - Low) / (High - Low) * 100

//initial lot
initLOT = 100

//profit step of the strategy to increase lot
stepPROFIT = 50

myLOT = max(initLOT,initLOT+ROUND((strategyprofit-stepPROFIT)/stepPROFIT))

IF NOT LongOnMarket AND STO<10 THEN
  BUY myLOT CONTRACTS AT MARKET
ENDIF

If LongOnMarket AND Close>High[1] THEN
  SELL AT MARKET
ENDIF
Comments
You must be logged in to post a comment.

je trouve cette stratégie interessante même si le qqq en question etf n'a pas beaucoup de volume de transaction toutefois pour améliorer le code originel, j'y connais rien, aurriez vous nicolas ou alfredo peut la gentillesse quand vous aurez le temps d'intégrer vos modifications proposés au code d'origine, pour en faire bénéficier tous le monde ? est ce possible NA

thank for the council, when i do start the strategie on Italy at 1h some mornings happen that i find the sistem interrupt with the error, but I' think that in the night the graph does not form some candle, maybe I'should make the strategy work from the 09:00 to 17:00 because the results are better, what do you think?
I do not have any error Alfredo, even while testing on 150000 bars in the past. By the way, you should use EXITSHORT : http://www.prorealcode.com/documentation/exitshort/ to exit a short position. I have change your code accordingly :
defparam cumulateorders=false

STO = (Close - Low) / (High - Low) * 100

IF NOT LongOnMarket AND STO<10 THEN
  BUY 2 CONTRACTS AT MARKET
ENDIF

If LongOnMarket AND Close>High[1] THEN
  SELL AT MARKET
ENDIF

if not shortonmarket and sto>90 then
  sellshort 2 contracts at market
endif

if shortonmarket and close<low[1] then
  exitshort at market
endif

set stop $loss 250
Where does your error appear? Is it a ProRealTime window?
Yes, thi is code modified
defparam cumulateorders=false
STO = (Close - Low) / (High - Low) * 100
IF NOT LongOnMarket AND STO<10 THEN
BUY 2 CONTRACTS AT MARKET
ENDIF
If LongOnMarket AND Close>High[1] THEN
SELL AT MARKET
ENDIF
if not shortonmarket and sto>90 then
sellshort 2 contracts at market
endif
if shortonmarket and close<low[1] then
buy at market
endif
set stop $loss 250
I find this strategy interesting even if the qqq in question etf does not have much transaction volume but to improve the original code, I know nothing about it, would you nicolas or alfredo can be kind when you have time to integrate your proposed changes to the original code, to benefit everyone? is it possible NA