






STORM - Short On Rising Markets
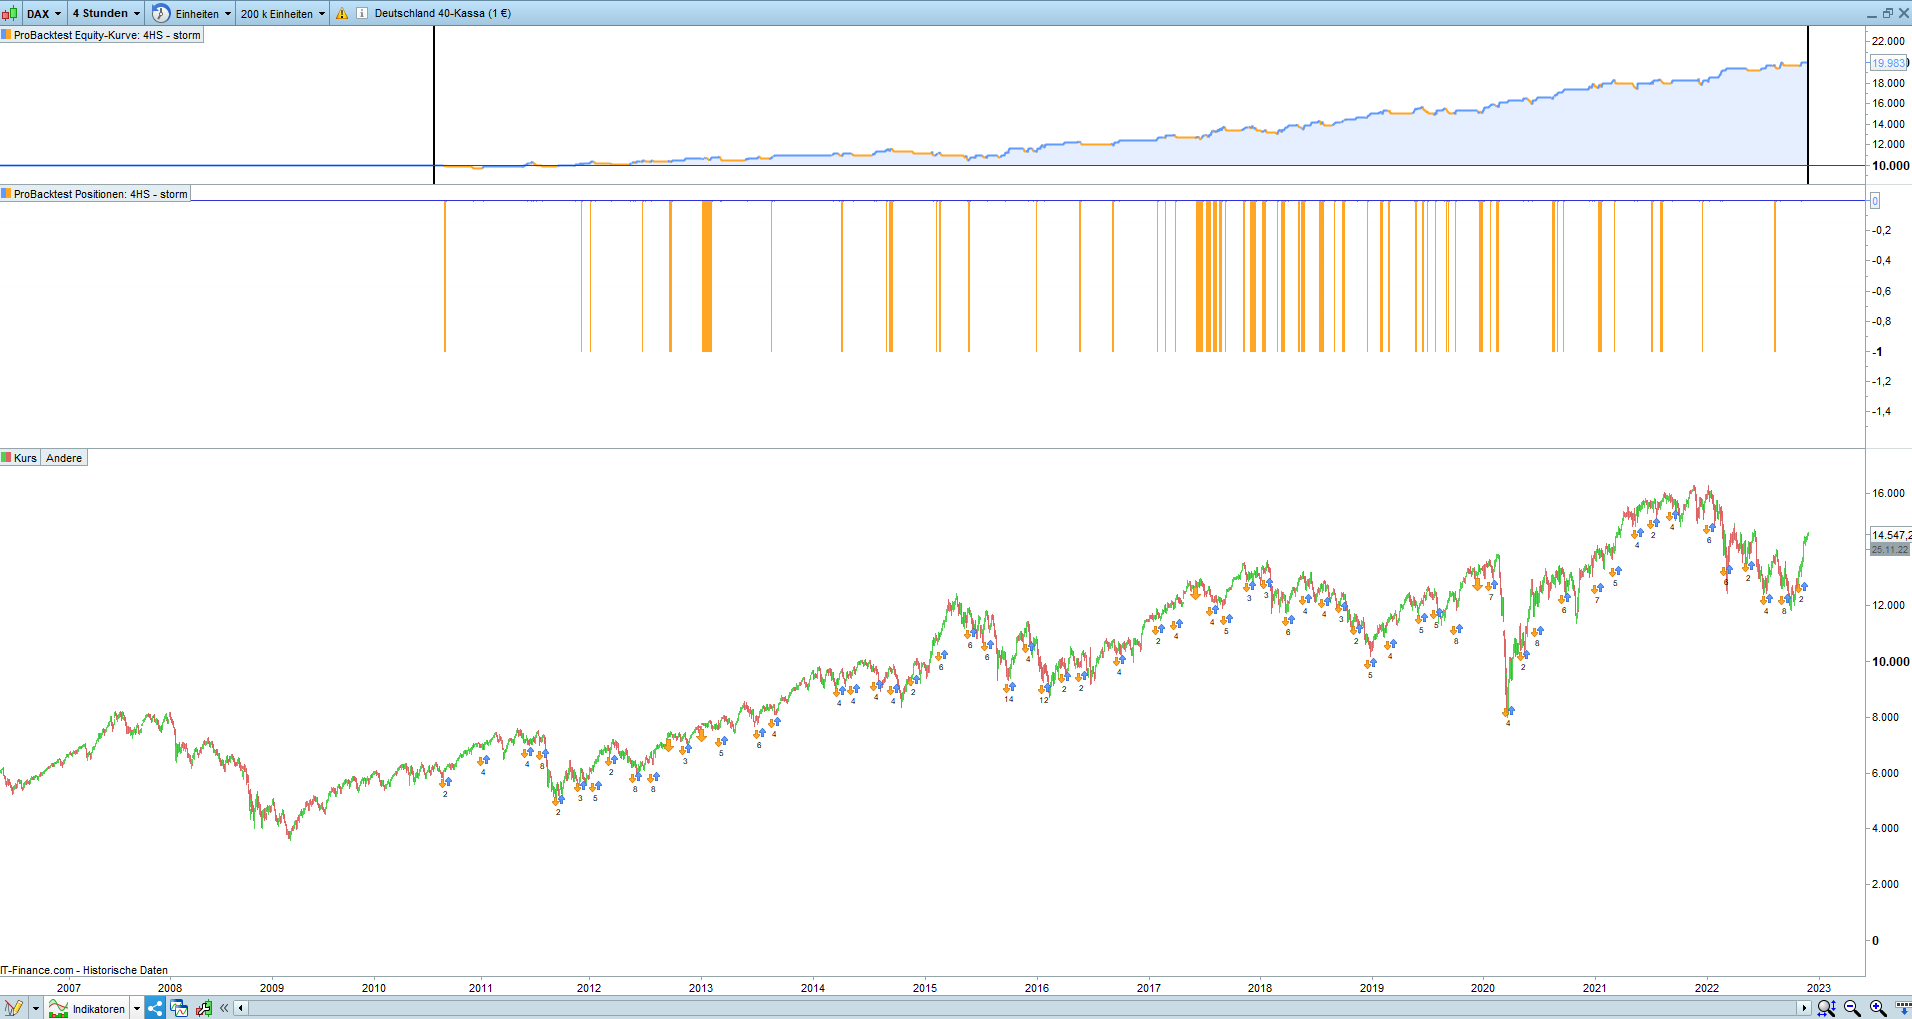
It’s pretty simple.
We take a fast average and a slow average.
We set two filters: the ATR and the time.
Now if the fast average is above the slow average and we get a simple 3 candle reversal we sell.
There is a fifty fifty chance, but this time we win.
//------------------------------------------------------------------
// OnlyShort Strategy on Dax
// Dax 1 Euro Mini
// TimeZone europe, berlin
// TimeFrame 4H
// MainCode : 4HS STORM - ShorT On Rising Markets
// created and coded by JohnScher
//------------------------------------------------------------------

defparam cumulateorders = false // works with true too

once ordersize = 1

//Pentuple Exponential Moving Average
period1 = 50
Period = MAX(Period1, 1)
MA1 = ExponentialAverage[Period](close)
MA2 = ExponentialAverage[Period](MA1)
MA3 = ExponentialAverage[Period](MA2)
MA4 = ExponentialAverage[Period](MA3)
MA5 = ExponentialAverage[Period](MA4)
MA6 = ExponentialAverage[Period](MA5)
MA7 = ExponentialAverage[Period](MA6)
MA8 = ExponentialAverage[Period](MA7)

PEMA = (8 * MA1) - (28 * MA2) + (56 * MA3) - (70 * MA4) + (56 * MA5) - (28 * MA6) + (8 * MA7) - MA8

//Hull Moving Average
period2 = 100
Period2 = MAX(Period2, 1)
HMA = WeightedAverage[ROUND(SQRT(Period2))](2 * WeightedAverage[ROUND(Period2 / 2)](close) - WeightedAverage[Period2](close))

// filter time
tm = openmonth <> 4 and openmonth <> 10
td = opendayofweek >= 2 and opendayofweek <= 5
tt = time >= 090000 and time <= 210000

// conditions
c1 = close > PEMA
c2 = PEMA > HMA

c3 = close < close[1] // 3-candle-revers, could be tested with some bearish candlestick pattern
c4 = close[2] < close[1]

c5 = averagetruerange [5] > 40 // filter, someone could be find betterone

// maincode
if tm and td and tt then
if c1 and c2 and c3 and c4 and c5 then
sellshort ordersize contracts at market
endif
endif

// fifty fifty chance
set stop %loss 2
set target %profit 2

// no trailing, no strategyprofit, no ...
Comments
You must be logged in to post a comment.

As a percentage of the price, here 2%. StopLoss as well as TargetProfit. SL and TP come from my basic approach to trading. Every time we have a 50/50 chance to win a trade with the same SL and same TP. In the end over countless trades we have to suffer a loss because of the spread. And now add the conditions at which we enter a trade. If we enter the trade on our conditions, the scales tip in our favor. // fifty fifty chance set stop %loss 2 set target %profit 2

With averages you can play around a lot, also in the lower timeframes, there are dozens possibilities. Compare averages here - https://www.prorealcode.com/prorealtime-trading-strategies/optimization-ma-cross-machine-learning/ To keep it simple I use here 2 known averages in default settings and set the filters time and ATR. nothing completly indifferent
Not a great OOS...