






The "Winning Pips System"
Hello everyone,
I found this strategy called ” Winning Pips System” (you can see it just by searching “winning pips system” on Google).
The strategy seemed profitable and I wanted to test it.
Disappointment :
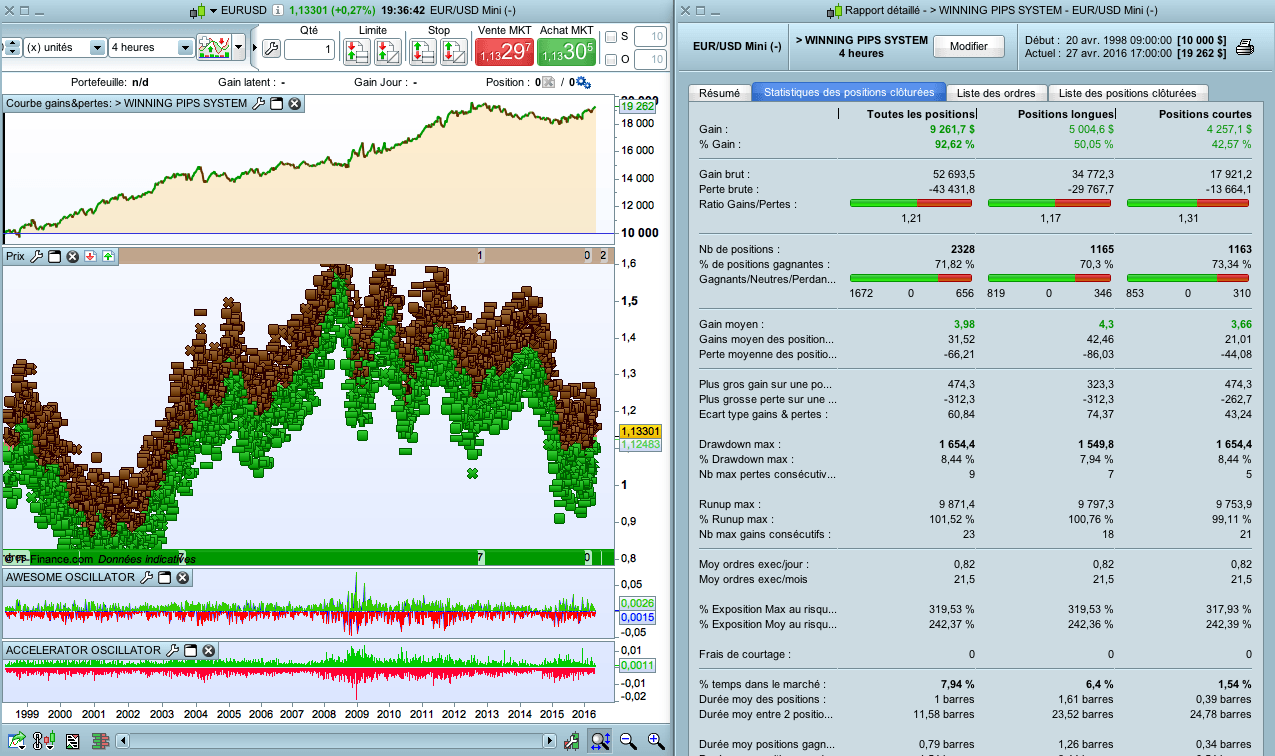
– It loses below the H4 timeframe, because of the spread (if there was no spread, it would be winning in H1)
– To be a winner, the take profit must be 2 times more little than the stop loss. However, even with a 1.5 point spread on EUR/USD (see backtest ), the strategy is profitable.
No doubt it is improvable .
It’s your turn !
DEFPARAM CumulateOrders = False

// TAILLE DES POSITIONS
N = 2

// DEFINITION DES INDICATEURS
AO = Average[5](medianprice) - Average[34](medianprice)
AC = AO - Average[5](AO)
PSAR = SAR[0.02,0.02,0.2]

// 1 SEUL TRADE par changement de SAR
IF close crosses over PSAR THEN
 phase = 1
ELSIF close crosses under PSAR THEN
 phase = -1
ENDIF


// ACHAT
ca1 = AO > AO[1]
ca2 = AC > AC[1]
ca3 = close > PSAR

IF ca1 AND ca2 AND ca3 and phase = 1 THEN
 buy N shares at market
 amplitude = close - low
 phase = 0
ENDIF

// VENTE
cv1 = AO < AO[1]
cv2 = AC < AC[1]
cv3 = close < PSAR

IF cv1 AND cv2 AND cv3 and phase = -1 THEN
 sellshort N shares at market
 amplitude = close - low
 phase = 0
ENDIF

// Stop Loss and Take Profit
SET STOP LOSS amplitude
SET TARGET PROFIT amplitude*0.5

// Stop loss au SAR
sell at PSAR STOP
exitshort at PSAR STOP
Comments
You must be logged in to post a comment.

Bonjour,
Tu as raison, il faut faire attention à la fiabilité de certains backtests. Le problème du SL et du TP sur la même bougie est bien connu sur ProRealTime, une prochaine version devrait corriger ce problème. Ceux qui comme nous codent régulièrement connaissent bien le problème, nous savons rester critiques devant un backtest "trop parfait".
Je vérifie que ce problème n'existe pas sur les backtests que je publie, et avant de me lancer en réel je teste mes stratégies.
Après tout, ça fait maintenant 3 ans que j'utilise deux stratégies qui avaient été backtestées sur PRT par mes soins, je m'y suis fiée à la lettre, et ça fait 3 ans que je gagne, je ne vois pas pourquoi je changerais... (stratégies en graphes Daily, jamais d'entrée et sortie sur la même bougie, une seule position à la fois, donc aucun problème pour le backtest). Je pense que > 80% des traders à domicile / amateurs ne peuvent pas en dire autant.
Belle journée à tous

Bonjour à tous,
Je suis, en général, assez effaré de voir cette course au meilleur backtest, à croire qu'il n'y a pas de traders ! Car le gros problème des backtests, c'est leur fiabilité. Il suffit de décortiquer les ordres "tests" pour s'apercevoir que beaucoup de positions données gagnantes sont en fait ...perdantes. Le target profit, s'il est atteint dans le timeframe, considère le trade gagnant, même si le stop loss est atteint avant. On peut donc aller vers beaucoup de désillusions, même avec de bons backtests. Donc avant de se lancer : testez les tests !
Hello.
It's not much better, I think.
Although this strategy is interesting, I don't find it profitable. My own codes (daily timeframe) make > 25% each year, this one make less than 6% each year...
I think that the "End of Day USD/JPY" that I did post before is more profitable.

....i have optimized with 1.5 spread....
Hi,
I have oprimized on EURUSD MINI starting from January 2016.
Best result with low drawdown:
TF 3H
AO = Average[10](medianprice) - Average[32](medianprice)
AC = AO - Average[10](AO)
TF 4H
AO = Average[5](medianprice) - Average[32](medianprice)
AC = AO - Average[5](AO)
I think to start these strategy in real account...what do you think ?
Tanks
Emanuele

Hi Doctrading!
I did a backtest and a little change from amplitude*0.5 to amplitude*1.7 (Profit) with this results: :O
http://www.prorealcode.com/wp-content/uploads/2015/07/USD-Wining-pips-.png
Hello. Results are better with amplitude * 0.5
Less drawdown, best profit factor on my test.
But BEWARE ! You are using the test on EUR/USD, I am using it on EUR/USD MINI-CONTRACT.
So you're not just using n = 2, but n = 20. The drawdown is inacceptable (more than the initial capital).
Don't forget also to set the SPREAD.
Best Regards,
Hello,
No, I don't use this strategy on real account, because my own strategies (that you can see on my website) in real account are FAR better, and not on forex but on indexes / stocks.
But I post some codes here, because I'm still looking to making a good forex strategy, so I test different ones.
Best regards,
Marc