Havent thought about using seasonality before so thanks for the info!
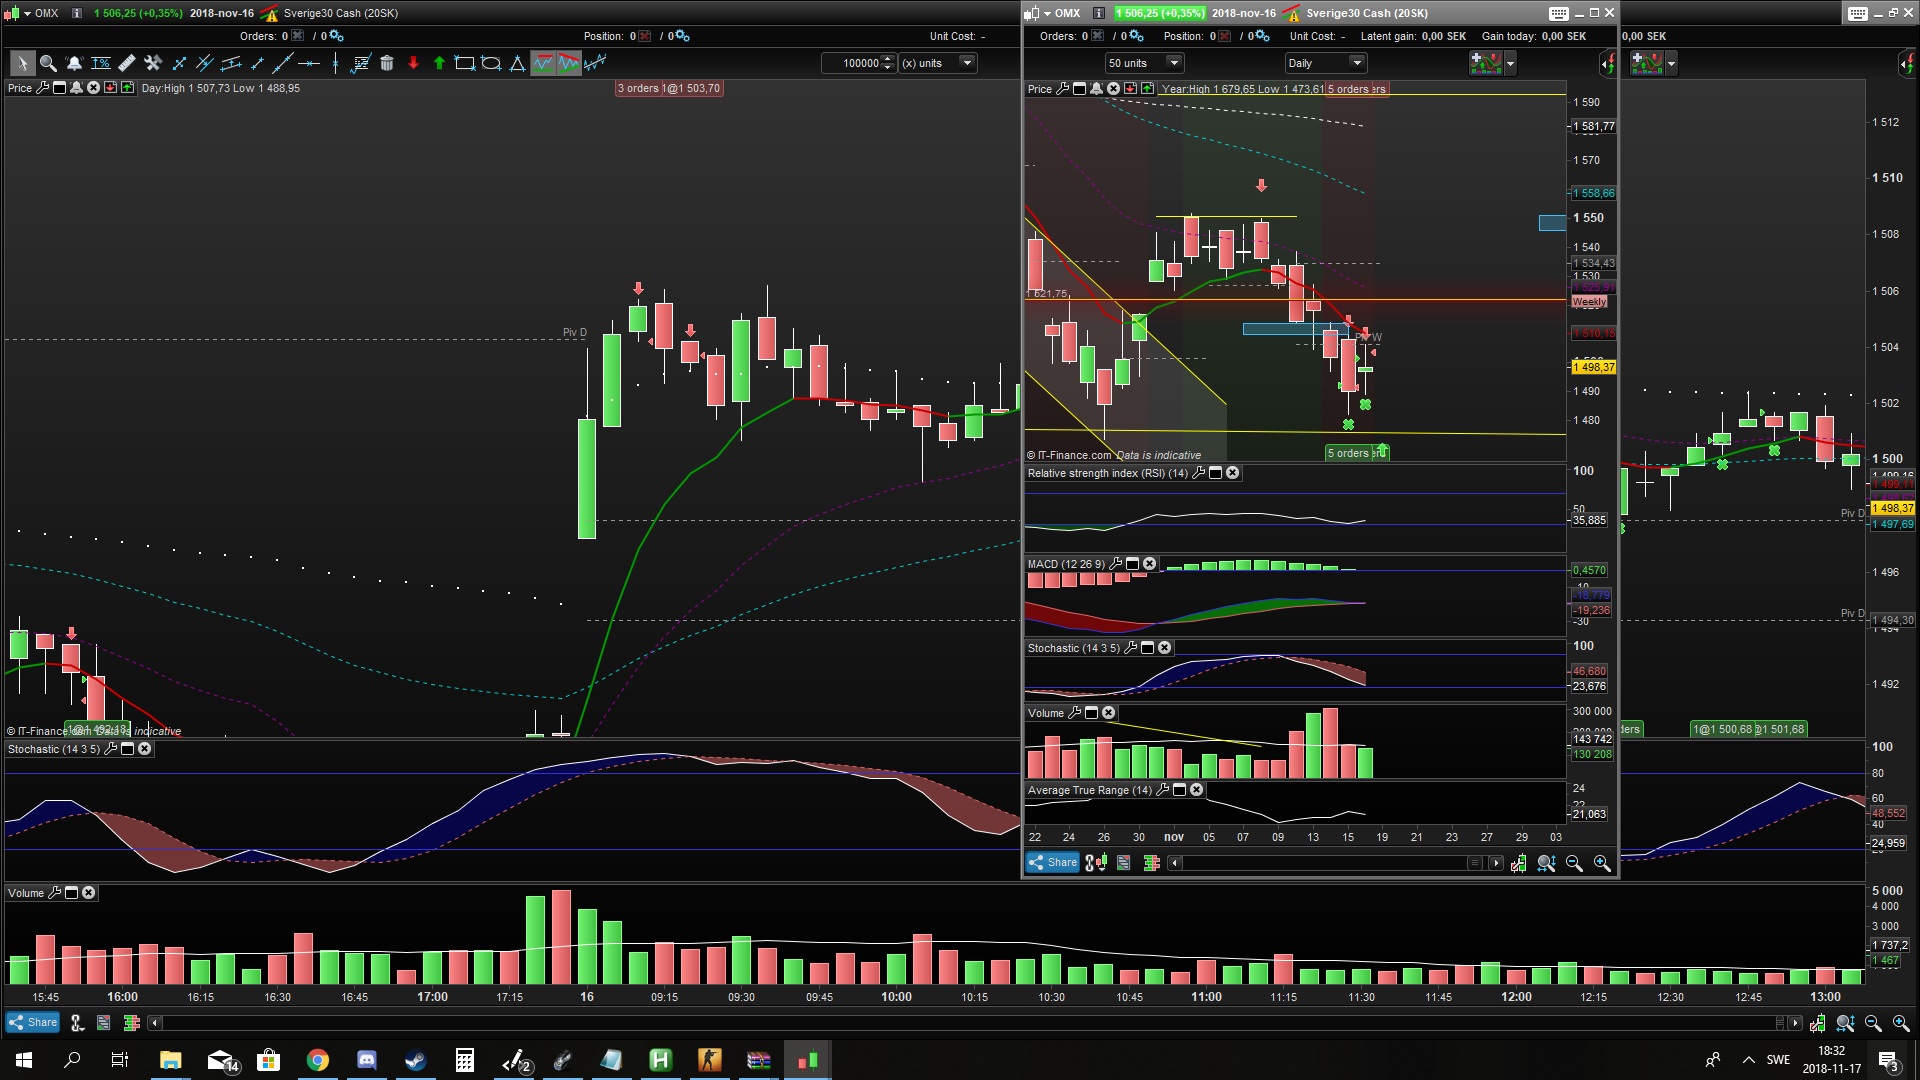
how come it takes a short on this trade? Look at my pic, opens up above x points. High of that candle is lower than lowest high of prev 2 daily?
how come it takes a short on this trade? Look at my pic, opens up above x points. High of that candle is lower than lowest high of prev 2 daily?
thah should be a long?
If High > Dayopen+nopl Then
Mclong=1
 Paul
Participant
Master
@ullle73, could you plz provide the settings you used and modified?
used the original code you did, from dax 3 min
L    = 0.88 // % Stoploss
PT    = 1.41 // % Profit Target
MFETS = 0.35 // % Mfe Trailing Stop
BES   = 0.35 // % Break Even Stop
BESMP = 0.05 // % Break Even Stop Minimum Profit
WTSMP = 0.50 // % Williams Trailing Stop Minimum Profit If Mfe Trailing Stop Is Not Used
ETD   = 0    //   Exclude a Trade Day; Sunday = 0
If Usepercentage Then
Nopl=((Dayopen*0.15)/100)/pointsize
Nops=((Dayopen*0.15)/100)/pointsize
Else
Nopl=13 //number of points long
Nops=14 //number of points short
Endif
These are my settings for time frame 3 minutes. Best result with optimization and WFA analysis with 7 period.
Nopl and Nops are the point that the system add to Dayopen (Open of candle of 09:00) in order to test for the high for each candles starting from 9:00 until 10:00
With the copy and paste I have made a mistak…replace L with SL…sorry
PaulParticipant
Master
@ullle73, I can’t duplicate your trade, but here’s a quick indicator code which can be used to understand trades.
TimeOpen=090000
nopL=2
nopS=2

If time = TimeOpen then
BaseLine=open
BuyLine=BaseLine+nopL
ShortLine=BaseLine-nopS
endif

RETURN BaseLine COLOURED(0,0,0) as "BaseLine", BuyLine COLOURED(0,128,0) as "BuyLine", ShortLine COLOURED(255,0,0) as "ShortLine"
If you add this to the pricechart, you will see that the open is taken 1 bar before 9u am.
@ullle73, I can’t duplicate your trade, but here’s a quick indicator code which can be used to understand trades.
TimeOpen=090000
nopL=2
nopS=2
If time = TimeOpen then
BaseLine=open
BuyLine=BaseLine+nopL
ShortLine=BaseLine-nopS
endif
RETURN BaseLine COLOURED(0,0,0) as “BaseLine”, BuyLine COLOURED(0,128,0) as “BuyLine”, ShortLine COLOURED(255,0,0) as “ShortLine”
TimeOpen=090000
nopL=2
nopS=2
If time = TimeOpen then
BaseLine=open
BuyLine=BaseLine+nopL
ShortLine=BaseLine–nopS
endif
RETURN BaseLine COLOURED(0,0,0) as “BaseLine”, BuyLine COLOURED(0,128,0) as “BuyLine”, ShortLine COLOURED(255,0,0) as “ShortLine”
If you add this to the pricechart, you will see that the open is taken 1 bar before 9u am.
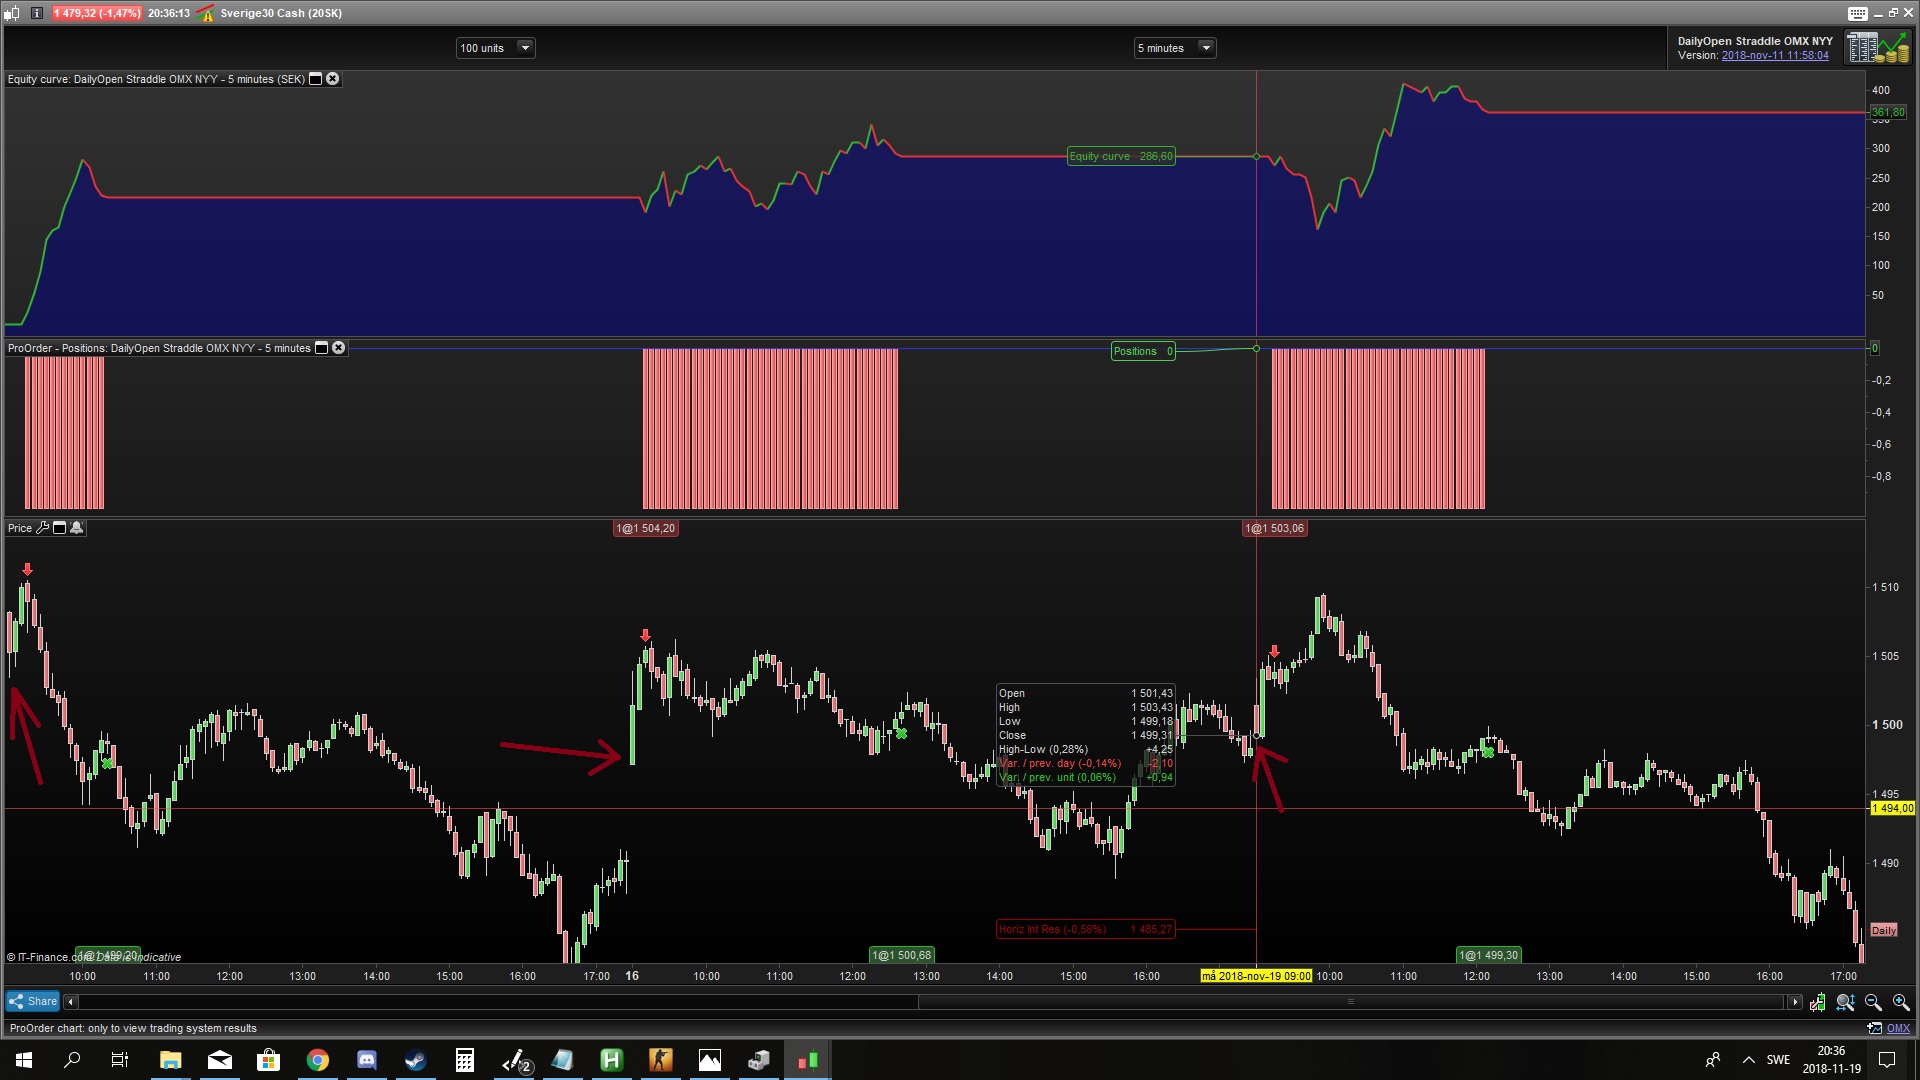
what? no? in my pic it shows the daily on the front pic, and the big pic behind is 5 min.
so if it opens down 4 points, and my settings on nopl/nops = 4, it only takes longs? and if it opens up by 4 points, it only takes shorts?
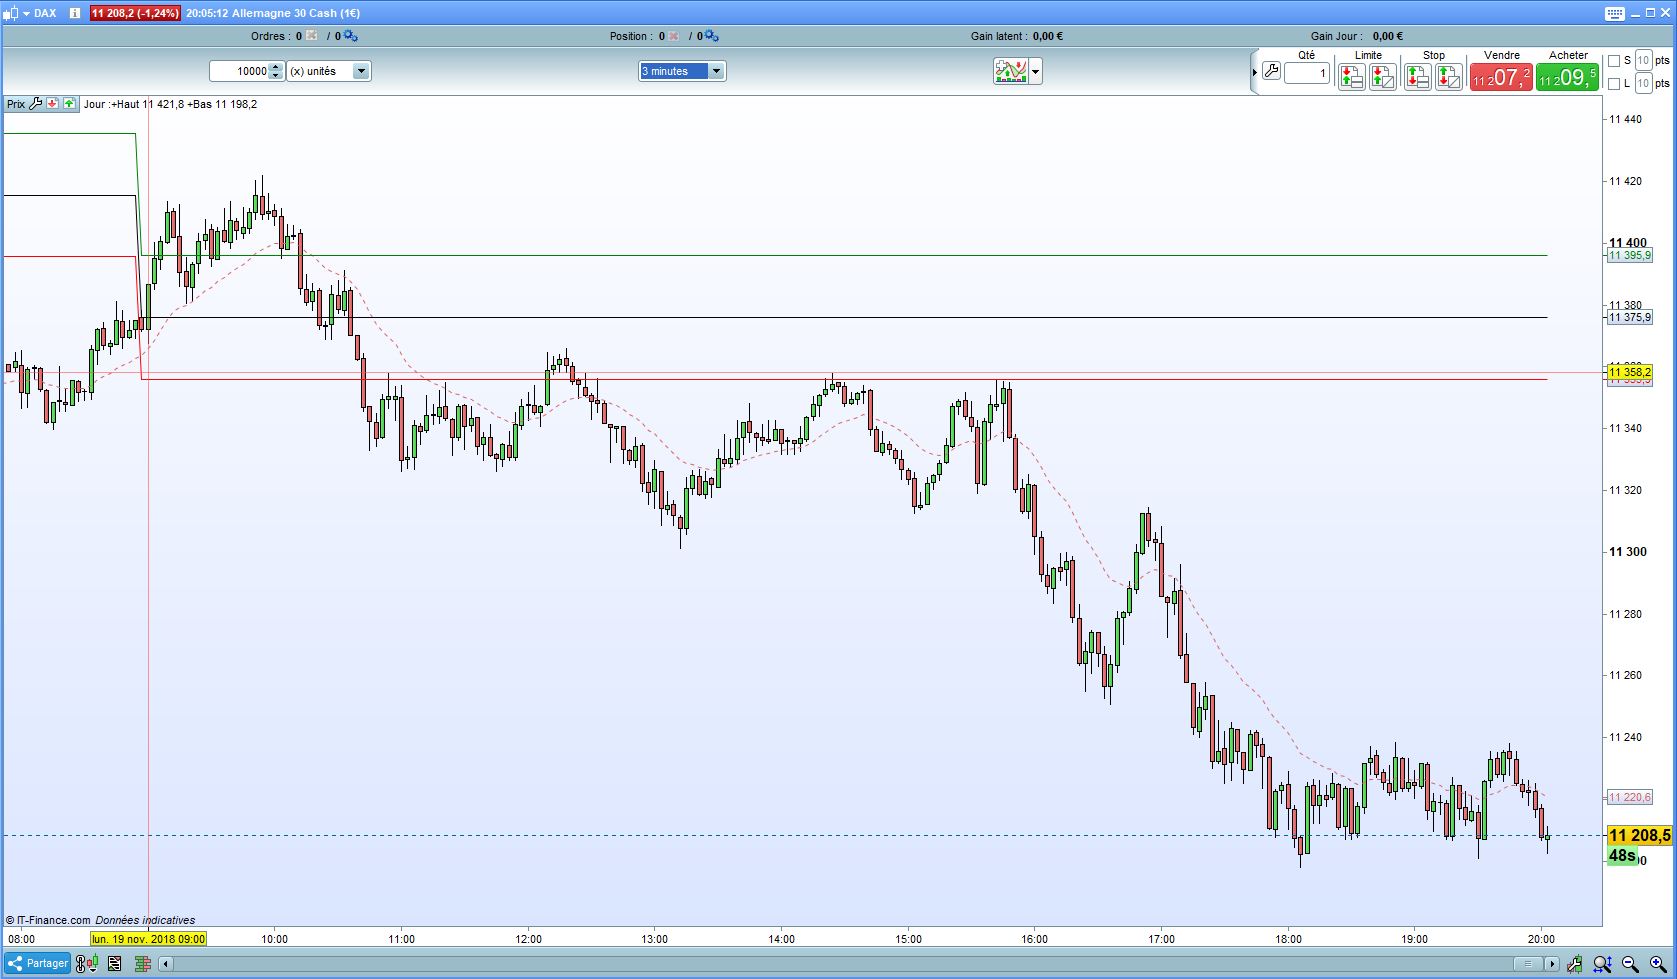
Hi, this picture may help you.
thx.
Hi, this picture may help you.
thx.
so it decides to long/short based on what line gets hit the first? If price reach green it takes a short? and if it reaches red first, it takes a long?
“At 9’ am the strategy defines the open and buys x points above or sellshort x points below, whichever comes first.
The assumption is, that once it’s opened, there is high probability that it continues at least x points in that direction.”
This does not seem correct. Look at my picture, as Paul wrote in the original text, if price goes x points above open, it should be a long? my system takes shorts when that happens
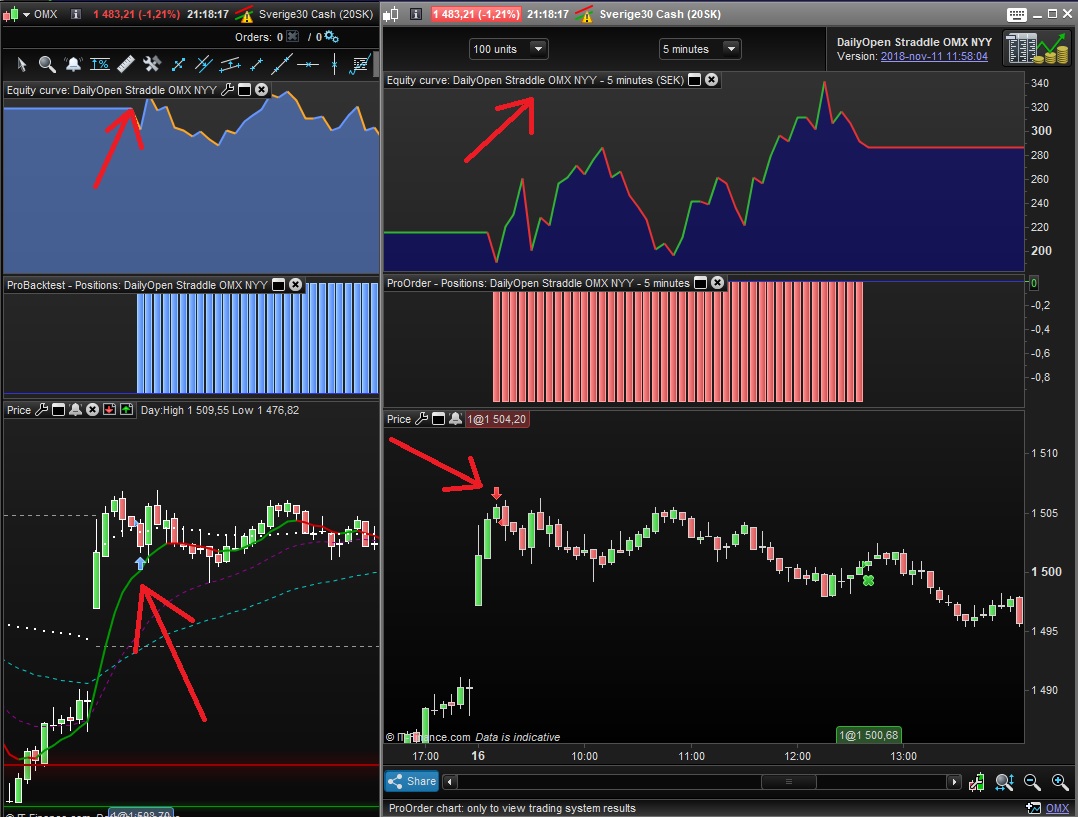
something is really off here. When i look at my code who got in short yesterday, here is the code:
//-------------------------------------------------------------------------
// Main code : DailyOpen Straddle OMX NYY
//-------------------------------------------------------------------------
//-------------------------------------------------------------------------
// Main Code : Straddle Dayopen V2.0
//-------------------------------------------------------------------------
// Test On DAX 30 Cash 10 Minute Timeframe 200k bars or from 1/1/2015

// Common Rules
Defparam Cumulateorders = False
Defparam Preloadbars = 1000

// On/off
Extratradecriteria   = 1 // I.e. Long; Only Enters When The Current Bar High Is Lower Then The Lowest Daily High From Today, Yesterday And Day Before.
Usepercentage        = 0 // The Minimum Difference In Percentage [[1] From Dayopen Or In Points [0] From Dayopen
Mfetrailing          = 1 // Mfe Trailing Stop
Wtrailing            = 1 // Williams 3 Bar Trailing Stop
Breakevenstop        = 1 // Breakevenstop, Move Stoploss When Position Is In Profit.
Excludefirsttwoweeks = 1 // Exclude The First 2 Weeks Of Every Year (Weeknumber 1 And 2)

// Settings
Positionsize = 1
SL    = 1.00 // % Stoploss
PT    = 1.50 // % Profit Target
MFETS = 0.35 // % Mfe Trailing Stop
BES   = 0.35 // % Break Even Stop
BESMP = 0.05 // % Break Even Stop Minimum Profit
WTSMP = 0.50 // % Williams Trailing Stop Minimum Profit If Mfe Trailing Stop Is Not Used
ETD   = 0    //   Exclude a Trade Day; Sunday = 0
If Usepercentage Then
Nopl=((Dayopen*0.15)/100)/pointsize
Nops=((Dayopen*0.15)/100)/pointsize
Else
Nopl=2 //number of points long
Nops=2 //number of points short
Endif

// Day & Time
Once Entertime = 090000
Once Lasttime  = 100000
Once Closetime = 240000 // Greater Then 23.59 Means It Continues Position Overnight
Once Closetimefr=173000

If Excludefirsttwoweeks=1 Then
If Year=2015 And Month=1 And (Day>=1 And Day<=18) Then
Notrading = 1
Elsif Year=2016 And Month=1 And (Day>=1 And Day<=24) Then
Notrading = 1
Elsif Year=2017 And Month=1 And (Day>=1 And Day<=22) Then
Notrading = 1
Elsif Year=2018 And Month=1 And (Day>=1 And Day<=21) Then
Notrading = 1
Elsif Year=2019 And Month=1 And (Day>=1 And Day<=20) Then
Notrading = 1
Else
Notrading = 0
Endif
Endif

Tt1 = Time >= Entertime
Tt2 = Time <= Lasttime
Tradetime = Tt1 And Tt2 and Notrading = 0 And Dayofweek <> ETD

// Reset At Start
If Intradaybarindex = 0 Then
Longtradecounter = 0
Shorttradecounter = 0
Tradecounter = 0
Mclong = 0
Mcshort = 0
Endif

// [pc] Position Criteria
Pclong  = Countoflongshares < 1 And Longtradecounter < 1 And Tradecounter < 1
Pcshort = Countofshortshares < 1 And Shorttradecounter < 1 And Tradecounter < 1

// [mc] Main Criteria
If Time = Entertime Then
Dayopen=open
Endif

If High > Dayopen+nopl Then
Mclong=1
Else
Mclong=0
Endif

If Low < Dayopen-nops Then
Mcshort=1
Else
Mcshort=0
Endif

// [ec] Extra Criteria
If Extratradecriteria Then
Min1 = Min(Dhigh(0),dhigh(1))
Min2 = Min(Dhigh(1),dhigh(2))

Max1 = Max(Dlow(0),dlow(1))
Max2 = Max(Dlow(1),dlow(2))

Eclong = High < Min(Min1,min2)
Ecshort = Low > Max(Max1,max2)
else
Eclong=1
Ecshort=1
Endif

// Long & Short Entry
If Tradetime Then
If Pclong and Mclong And Eclong Then
Buy Positionsize Contract At Market
Longtradecounter=longtradecounter + 1
Tradecounter=tradecounter+1
Endif
If Pcshort and Mcshort And Ecshort Then
Sellshort Positionsize Contract At Market
Shorttradecounter=shorttradecounter + 1
Tradecounter=tradecounter+1
Endif
Endif

// Break Even Stop
If Breakevenstop Then
If Not Onmarket Then
Newsl=0
Endif
If Longonmarket And close-tradeprice(1)>=((Tradeprice/100)*BES)*pipsize Then
Newsl = Tradeprice(1)+((Tradeprice/100)*BESMP)*pipsize
Endif
If Shortonmarket And Tradeprice(1)-close>=((Tradeprice/100)*BES)*pipsize Then
Newsl = Tradeprice(1)-((Tradeprice/100)*BESMP)*pipsize
Endif
If Newsl>0 Then
Sell At Newsl Stop
Exitshort At Newsl Stop
Endif
Endif

// Exit Mfe Trailing Stop
If Mfetrailing Then
Trailingstop = (Tradeprice/100)*MFETS
If Not Onmarket Then
Maxprice = 0
Minprice = Close
Priceexit = 0
Endif
If Longonmarket Then
Maxprice = Max(Maxprice,close)
If Maxprice-tradeprice(1)>=trailingstop*pipsize Then
Priceexit = Maxprice-trailingstop*pipsize
Endif
Endif
If Shortonmarket Then
Minprice = Min(Minprice,close)
If Tradeprice(1)-minprice>=trailingstop*pipsize Then
Priceexit = Minprice+trailingstop*pipsize
Endif
Endif
If Onmarket And Wtrailing=0 And Priceexit>0 Then
Sell At Market
Exitshort At Market
Endif
Endif

// Exit Williams Trailing Stop
If Wtrailing Then
Count=1
I=0
J=i+1
Tot=0
While Count<4 Do
Tot=tot+1
If (Low[j]>=low[i]) And (High[j]<=high[i]) Then
J=j+1
Else
Count=count+1
I=i+1
J=i+1
Endif
Wend

Basso=lowest[tot](Low)
Alto=highest[tot](High)

If Close>alto[1] Then
Ref=basso
Endif
If Close<basso[1] Then
Ref=alto
Endif

If Onmarket And Mfetrailing=0 And Positionperf>WTSMP Then
If Low[1]>ref And High<ref Then
Sell At Market
Endif
If High[1]<ref And Low>ref Then
Exitshort At Market
Endif
Endif

If Onmarket And Mfetrailing=1 And Priceexit>0 Then
If High<ref Then
Sell At Market
Endif
If Low>ref Then
Exitshort At Market
Endif
Endif
Endif

// Exit At Closetime
If Onmarket Then
If Time >= Closetime Then
Sell At Market
Exitshort At Market
Endif
Endif

// Exit At Closetime Friday
If Onmarket Then
If (Currentdayofweek=5 And Time>=closetimefr) Then
Sell At Market
Exitshort At Market
Endif
Endif

// Build-in Exit
Set Stop %loss SL
Set Target %profit PT

//graph 0 Coloured(300,0,0) As "Zeroline"
//graph (Positionperf*100)coloured(0,0,0,255) As "Positionperformance"
BUT when i backtest it today, it enters long, but on automatic it took a short?! why?