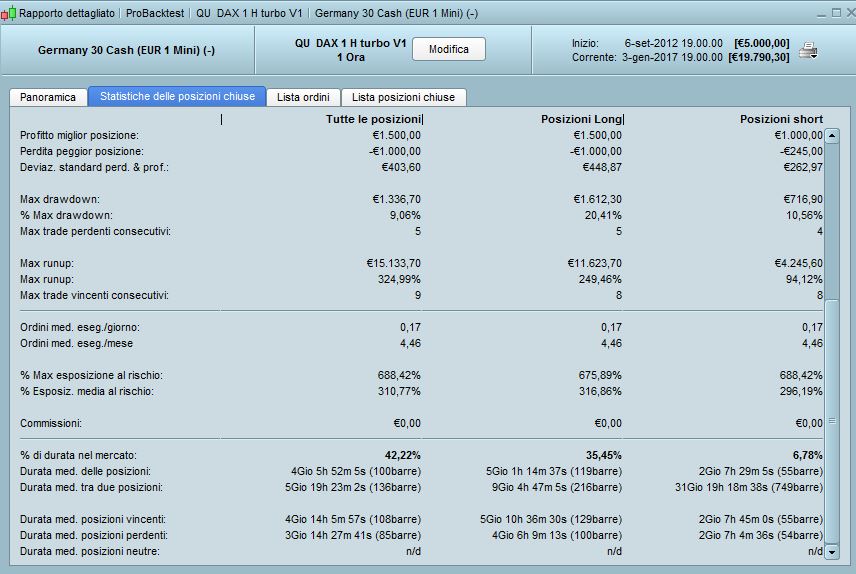
dopo vari mesi di prove… su conto demo tutti i sistemi provati danno esito negativo…. anche quelli con i risultati della simulazioni migliori … fanno tutti la stessa fine … ora mi chiedo … ma qualcuno che ha un sistema che gira in reale e che guadagna esiste con questa versione 10.2 ….
in attesa che esca la nuova versione…
grazie a chi vorrà rispondere …
saluti
Max
 ALE
Moderator
Master
Ciao Max
Hai provato Il sistema QU dax, QU ftse, Pathfinder V6?
ciao Ale,
no ancora no.. proverò anche questi..
il qu dax ho visto che ci sono 4 file da scaricare cosa li differenzia uno dall’altro … qu sell, qu buy, qu turbo,univ qu dax.. poi una versiona ottimizzata da miguel .. da quale devo partire …
grazie
ALEModerator
Master
Ciao
scarica
Qu buy / Qu sell/ Qu turbo
Miguel ha ottimizzato la la versione, su uno storico di 100.000 barre io l’ho costruita su 200.000 barre.
decidi tu quale usare.
ALEModerator
Master
Scusa dimenticavo anche il 4′ file univ
la strategia e Qu turbo, gli altri 3 file sono gli indicatori per far funzionare la strategia
perfetto grazie … adesso li carico in piattaforma…se ho bisogno ti disturbo …
la Pathfinder V 6 invece non l’ho trovata… ho trovato la versione fino V 3 se puoi indicarmi il link.
grazie ancora …
Max..
opss… ho visto che da oggi c’è la versione 10.3 cambia qualcosa per questi codici oppure si possono caricare e funzionano senza problemi …
grazie..
ALEModerator
Master
Ciao
io ho sempre la 10.2, potresti inviarmi copia del probacktest cosi che guardo?
grazie
Ale
ALEModerator
Master
Pathfinder v6 4h
//Trading System based on ProRealTime 10.2
// Breakout system triggered by previous daily, weekly and monthly high/low crossings with smart position management
// Version 6
// Instrument: DAX mini 4H, 9-21 CET, 2 points spread, account size 10.000 Euro, from August 2010

// ProOrder code parameter
DEFPARAM CUMULATEORDERS = true  // cumulate orders if not turned off
DEFPARAM PRELOADBARS = 10000

// define intraday trading window
ONCE startTime = 90000
ONCE endTime = 210000

// define instrument signalline with help of multiple smoothed averages
ONCE periodFirstMA = 5
ONCE periodSecondMA = 10
ONCE periodThirdMA = 3

// define filter parameter
ONCE periodLongMA = 300
ONCE periodShortMA = 50

// define position and money management parameter
ONCE positionSize = 1

Capital = 10000
Risk = 5 // in %
equity = Capital + StrategyProfit
maxRisk = round(equity * Risk / 100)

ONCE stopLossLong = 5.5 // in %
ONCE stopLossShort = 3.25 // in %
ONCE takeProfitLong = 3.25 // in %
ONCE takeProfitShort = 3.25 // in %

maxPositionSizeLong = MAX(45, abs(round(maxRisk / (close * stopLossLong / 100) / PointValue) * pipsize))
maxPositionSizeShort = MAX(45, abs(round(maxRisk / (close * stopLossShort / 100) / PointValue) * pipsize))

ONCE trailingStartLong = 2 // in %
ONCE trailingStartShort = 0.75 // in %
ONCE trailingStepLong = 0.2 // in %
ONCE trailingStepShort = 0.4 // in %

ONCE maxCandlesLongWithProfit = 16  // take long profit latest after 16 candles
ONCE maxCandlesShortWithProfit = 15  // take short profit latest after 15 candles
ONCE maxCandlesLongWithoutProfit = 30  // limit long loss latest after 30 candles
ONCE maxCandlesShortWithoutProfit = 12  // limit short loss latest after 12 candles

// define saisonal position multiplier for each month 1-15 / 16-31 (>0 - long / <0 - short / 0 no trade)
ONCE January1 = 3
ONCE January2 = 0
ONCE February1 = 3
ONCE February2 = 3
ONCE March1 = 3
ONCE March2 = 2
ONCE April1 = 3
ONCE April2 = 3
ONCE May1 = 1
ONCE May2 = 1
ONCE June1 = 2
ONCE June2 = 2
ONCE July1 = 3
ONCE July2 = 1
ONCE August1 = 1
ONCE August2 = 1
ONCE September1 = 3
ONCE September2 = 0
ONCE October1 = 3
ONCE October2 = 2
ONCE November1 = 2
ONCE November2 = 3
ONCE December1 = 3
ONCE December2 = 2

// calculate daily high/low (include sunday values if available)
dailyHigh = DHigh(1)
dailyLow = DLow(1)

// calculate weekly high/low
If DayOfWeek < DayOfWeek[1] then
weeklyHigh = Highest[BarIndex - lastWeekBarIndex](dailyHigh)
lastWeekBarIndex = BarIndex
ENDIF

// calculate monthly high/low
If Month[1] <> Month[2] then
//If Month <> Month[1] then
monthlyHigh = Highest[BarIndex - lastMonthBarIndex](dailyHigh)
monthlyLow = Lowest[BarIndex - lastMonthBarIndex](dailyLow)
lastMonthBarIndex = BarIndex
ENDIF

// calculate instrument signalline with multiple smoothed averages
firstMA = WilderAverage[periodFirstMA](close)
secondMA = TimeSeriesAverage[periodSecondMA](firstMA)
signalline = TimeSeriesAverage[periodThirdMA](secondMA)

// save position before trading window is open
If Time < startTime then
startPositionLong = COUNTOFLONGSHARES
startPositionShort = COUNTOFSHORTSHARES
EndIF

// trade only in defined trading window
IF Time >= startTime AND Time <= endTime THEN

// set saisonal multiplier
currentDayOfTheMonth = Date - ((CurrentYear * 10000) + CurrentMonth * 100)
midOfMonth = 15
IF CurrentMonth = 1 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = January1
ELSE
saisonalPatternMultiplier = January2
ENDIF
ELSIF CurrentMonth = 2 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = February1
ELSE
saisonalPatternMultiplier = February2
ENDIF
ELSIF CurrentMonth = 3 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = March1
ELSE
saisonalPatternMultiplier = March2
ENDIF
ELSIF CurrentMonth = 4 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = April1
ELSE
saisonalPatternMultiplier = April2
ENDIF
ELSIF CurrentMonth = 5 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = May1
ELSE
saisonalPatternMultiplier = May2
ENDIF
ELSIF CurrentMonth = 6 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = June1
ELSE
saisonalPatternMultiplier = June2
ENDIF
ELSIF CurrentMonth = 7 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = July1
ELSE
saisonalPatternMultiplier = July2
ENDIF
ELSIF CurrentMonth = 8 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = August1
ELSE
saisonalPatternMultiplier = August2
ENDIF
ELSIF CurrentMonth = 9 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = September1
ELSE
saisonalPatternMultiplier = September2
ENDIF
ELSIF CurrentMonth = 10 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = October1
ELSE
saisonalPatternMultiplier = October2
ENDIF
ELSIF CurrentMonth = 11 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = November1
ELSE
saisonalPatternMultiplier = November2
ENDIF
ELSIF CurrentMonth = 12 THEN
IF currentDayOfTheMonth <= midOfMonth THEN
saisonalPatternMultiplier = December1
ELSE
saisonalPatternMultiplier = December2
ENDIF
ENDIF

// define trading filters
// 1. use fast and slow averages as filter because not every breakout is profitable
f1 = close > Average[periodLongMA](close)
f2 = close < Average[periodLongMA](close)
f3 = close > Average[periodShortMA](close)

// 2. check if position already reduced in trading window as additonal filter criteria
alreadyReducedLongPosition = COUNTOFLONGSHARES  < startPositionLong
alreadyReducedShortPosition = COUNTOFSHORTSHARES < startPositionShort

// long position conditions
l1 = signalline CROSSES OVER monthlyHigh
l2 = signalline CROSSES OVER weeklyHigh
l3 = signalline CROSSES OVER dailyHigh
l4 = signalline CROSSES OVER monthlyLow

// short position conditions
s1 = signalline CROSSES UNDER monthlyHigh
s2 = signalline CROSSES UNDER dailyLow

// long entry with order cumulation
IF ( (l1 OR l4 OR l2 OR (l3 AND f2)) AND NOT alreadyReducedLongPosition) THEN

// check saisonal booster setup and max position size
IF saisonalPatternMultiplier > 0 THEN
IF (COUNTOFPOSITION + (positionSize * saisonalPatternMultiplier)) <= maxPositionSizeLong THEN
BUY positionSize * saisonalPatternMultiplier CONTRACT AT MARKET
ENDIF
ELSIF saisonalPatternMultiplier <> 0 THEN
IF (COUNTOFPOSITION + positionSize) <= maxPositionSizeLong THEN
BUY positionSize CONTRACT AT MARKET
ENDIF
ENDIF

stopLoss = stopLossLong
takeProfit = takeProfitLong

ENDIF

// short entry without order cumulation
IF NOT SHORTONMARKET AND ( (s1 AND f3) OR  (s2 AND f1) ) AND NOT alreadyReducedShortPosition THEN

// check saisonal booster setup and max position size
IF saisonalPatternMultiplier < 0 THEN
IF (COUNTOFPOSITION + (positionSize * ABS(saisonalPatternMultiplier))) <= maxPositionSizeShort THEN
SELLSHORT positionSize * ABS(saisonalPatternMultiplier) CONTRACT AT MARKET
ENDIF
ELSIF saisonalPatternMultiplier <> 0 THEN
IF (COUNTOFPOSITION + positionSize) <= maxPositionSizeLong THEN
SELLSHORT positionSize CONTRACT AT MARKET
ENDIF
ENDIF

stopLoss = stopLossShort
takeProfit = takeProfitShort

ENDIF

// stop and profit management
posProfit = (((close - positionprice) * pointvalue) * countofposition) / pipsize

numberCandles = (BarIndex - TradeIndex)

m1 = posProfit > 0 AND numberCandles >= maxCandlesLongWithProfit
m2 = posProfit > 0 AND numberCandles >= maxCandlesShortWithProfit
m3 = posProfit < 0 AND numberCandles >= maxCandlesLongWithoutProfit
m4 = posProfit < 0 AND numberCandles >= maxCandlesShortWithoutProfit

// take profit after max candles
IF LONGONMARKET AND (m1 OR m3) THEN
SELL AT MARKET
ENDIF
IF SHORTONMARKET AND (m2 OR m4) THEN
EXITSHORT AT MARKET
ENDIF

// trailing stop function (convert % to pips)
trailingStartLongInPoints = tradeprice(1) * trailingStartLong / 100
trailingStartShortInPoints = tradeprice(1) * trailingStartShort / 100
trailingStepLongInPoints = tradeprice(1) * trailingStepLong / 100
trailingStepShortInPoints = tradeprice(1) * trailingStepShort / 100

// reset the stoploss value
IF NOT ONMARKET THEN
newSL = 0
ENDIF

// manage long positions
IF LONGONMARKET THEN
// first move (breakeven)
IF newSL = 0 AND close - tradeprice(1) >= trailingStartLongInPoints * pipsize THEN
newSL = tradeprice(1) + trailingStepLongInPoints * pipsize
stopLoss = stopLossLong * 0.1
takeProfit = takeProfitLong * 2
ENDIF
// next moves
IF newSL > 0 AND close - newSL >= trailingStepLongInPoints * pipsize THEN
newSL = newSL + trailingStepLongInPoints * pipsize
ENDIF
ENDIF

// manage short positions
IF SHORTONMARKET THEN
// first move (breakeven)
IF newSL = 0 AND tradeprice(1) - close >= trailingStartShortInPoints * pipsize THEN
newSL = tradeprice(1) - trailingStepShortInPoints * pipsize
ENDIF
// next moves
IF newSL > 0 AND newSL - close >= trailingStepShortInPoints * pipsize THEN
newSL = newSL - trailingStepShortInPoints * pipsize
ENDIF
ENDIF

// stop order to exit the positions
IF newSL > 0 THEN
IF LONGONMARKET THEN
SELL AT newSL STOP
ENDIF
IF SHORTONMARKET THEN
EXITSHORT AT newSL STOP
ENDIF
ENDIF

// superordinate stop and take profit
SET STOP %LOSS stopLoss
SET TARGET %PROFIT takeProfit

ENDIF
ciao, ho caricato i 3 file descritti quando metto il 4 mi dice gia esistente … inoltre li mette tra gli indicatori e non tra i sistemi ..
cosa posso fare..
grazie ..
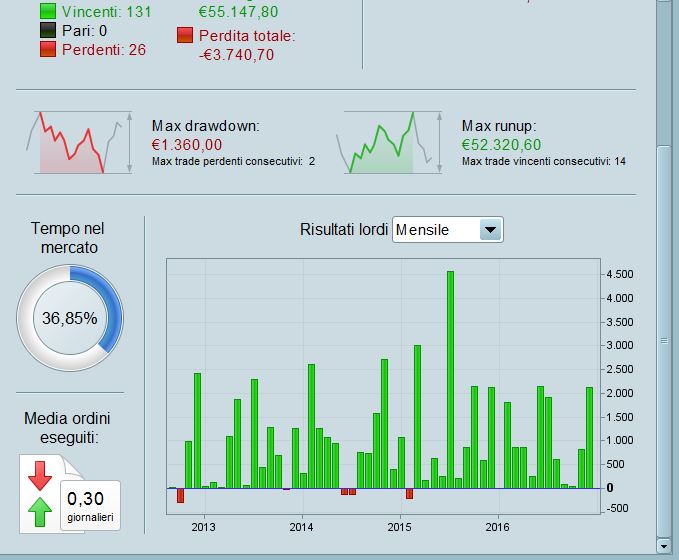
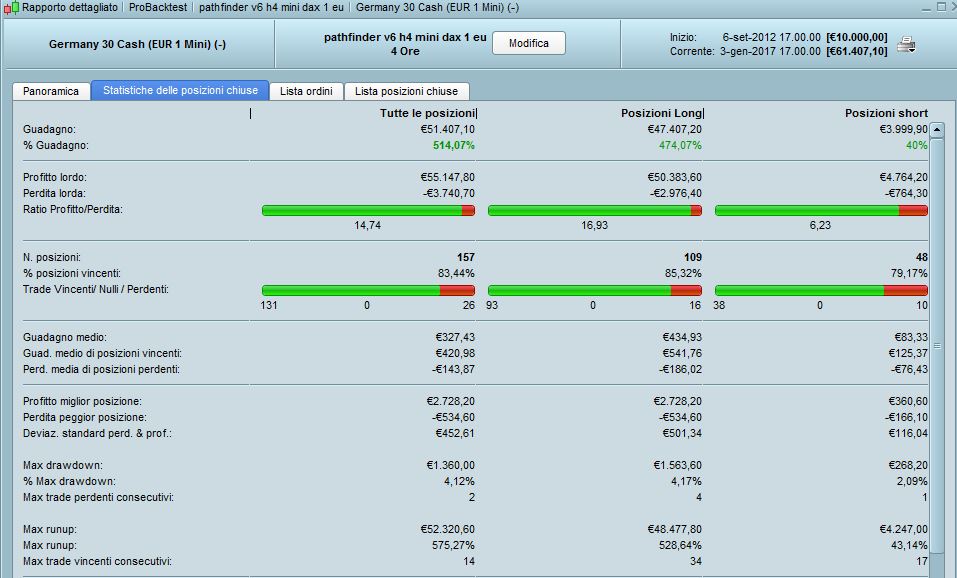
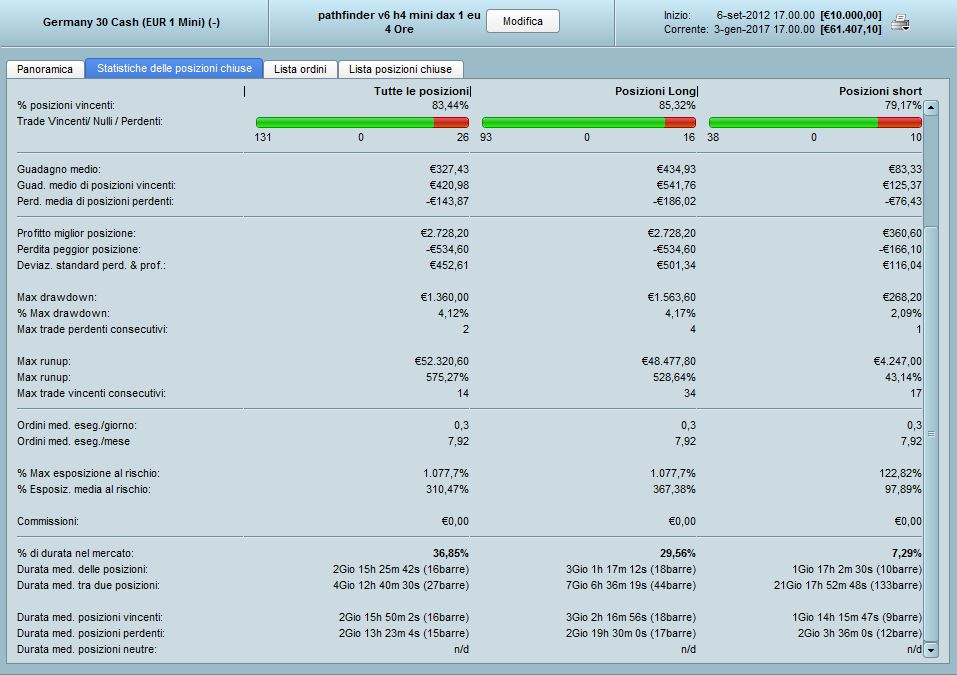
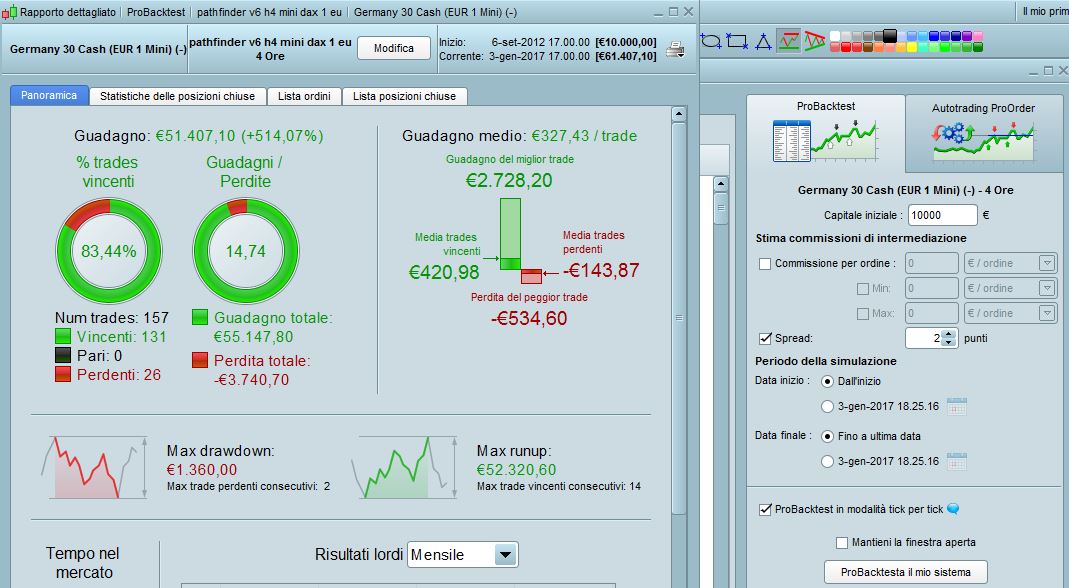
questo è il report del pathfinder 6v ho usato dax mini 1 euro
se ti serve altro dimmi pure ..
ALEModerator
Master
Ciao
OK gli indicatori sono presenti, ora dovresti trovare la strategia nel menu, ed avviarla. QU_DAX_TURBO, time frame 1h, DAX 1€ CFD INDICE
ok fatto .. ho provato a caricarlo sopra … quando mi chiede se voglio sostituire ho detto si .. ed ha funzionato è stato istallato …
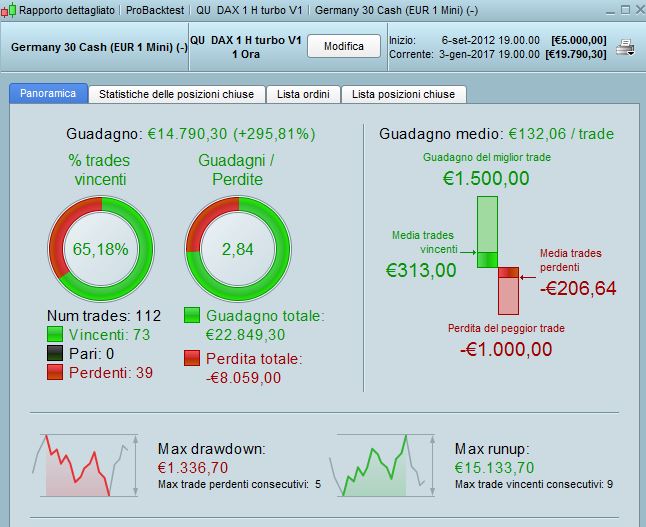
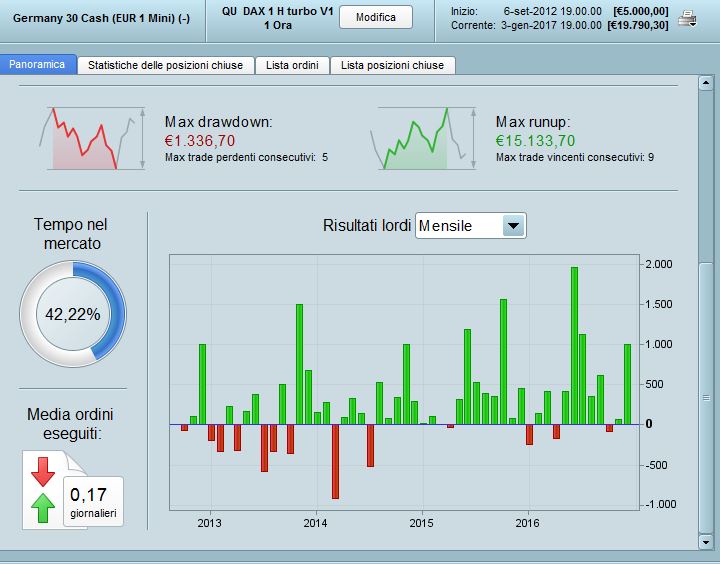
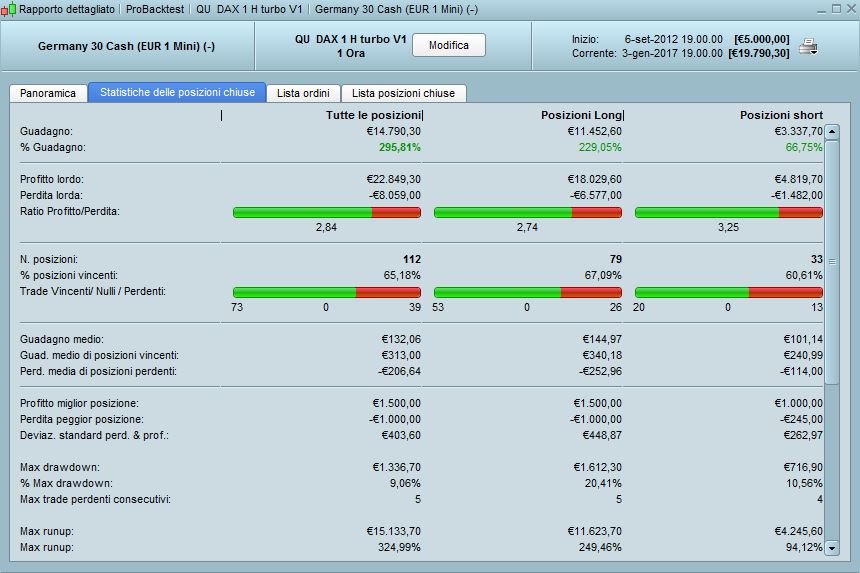
controlla se ho fatto bene … questi sono i report
spread 2
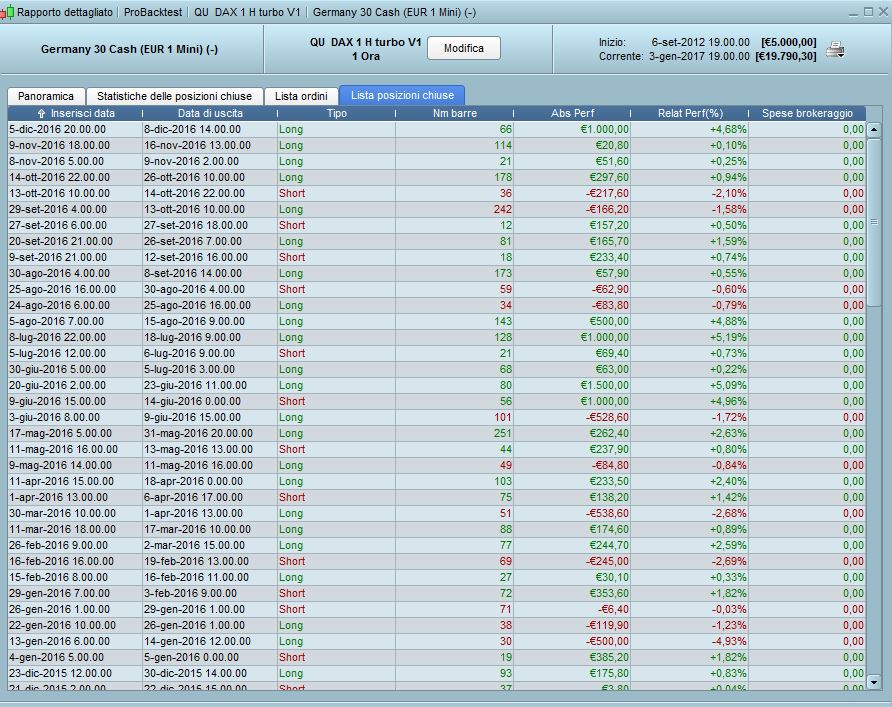
invio anche una copia delle ultime operazioni ..
ALEModerator
Master
Ciao
si è corretto, la strategia è molto semplice, ti è chiaro il funzionamento? osservando la posizione degli indicatori saprai quando il sistema entrerà a mercato all’apertura della candela successiva, ovviamente lavora su periodi piuttosto lunghi, per cui è overnight.